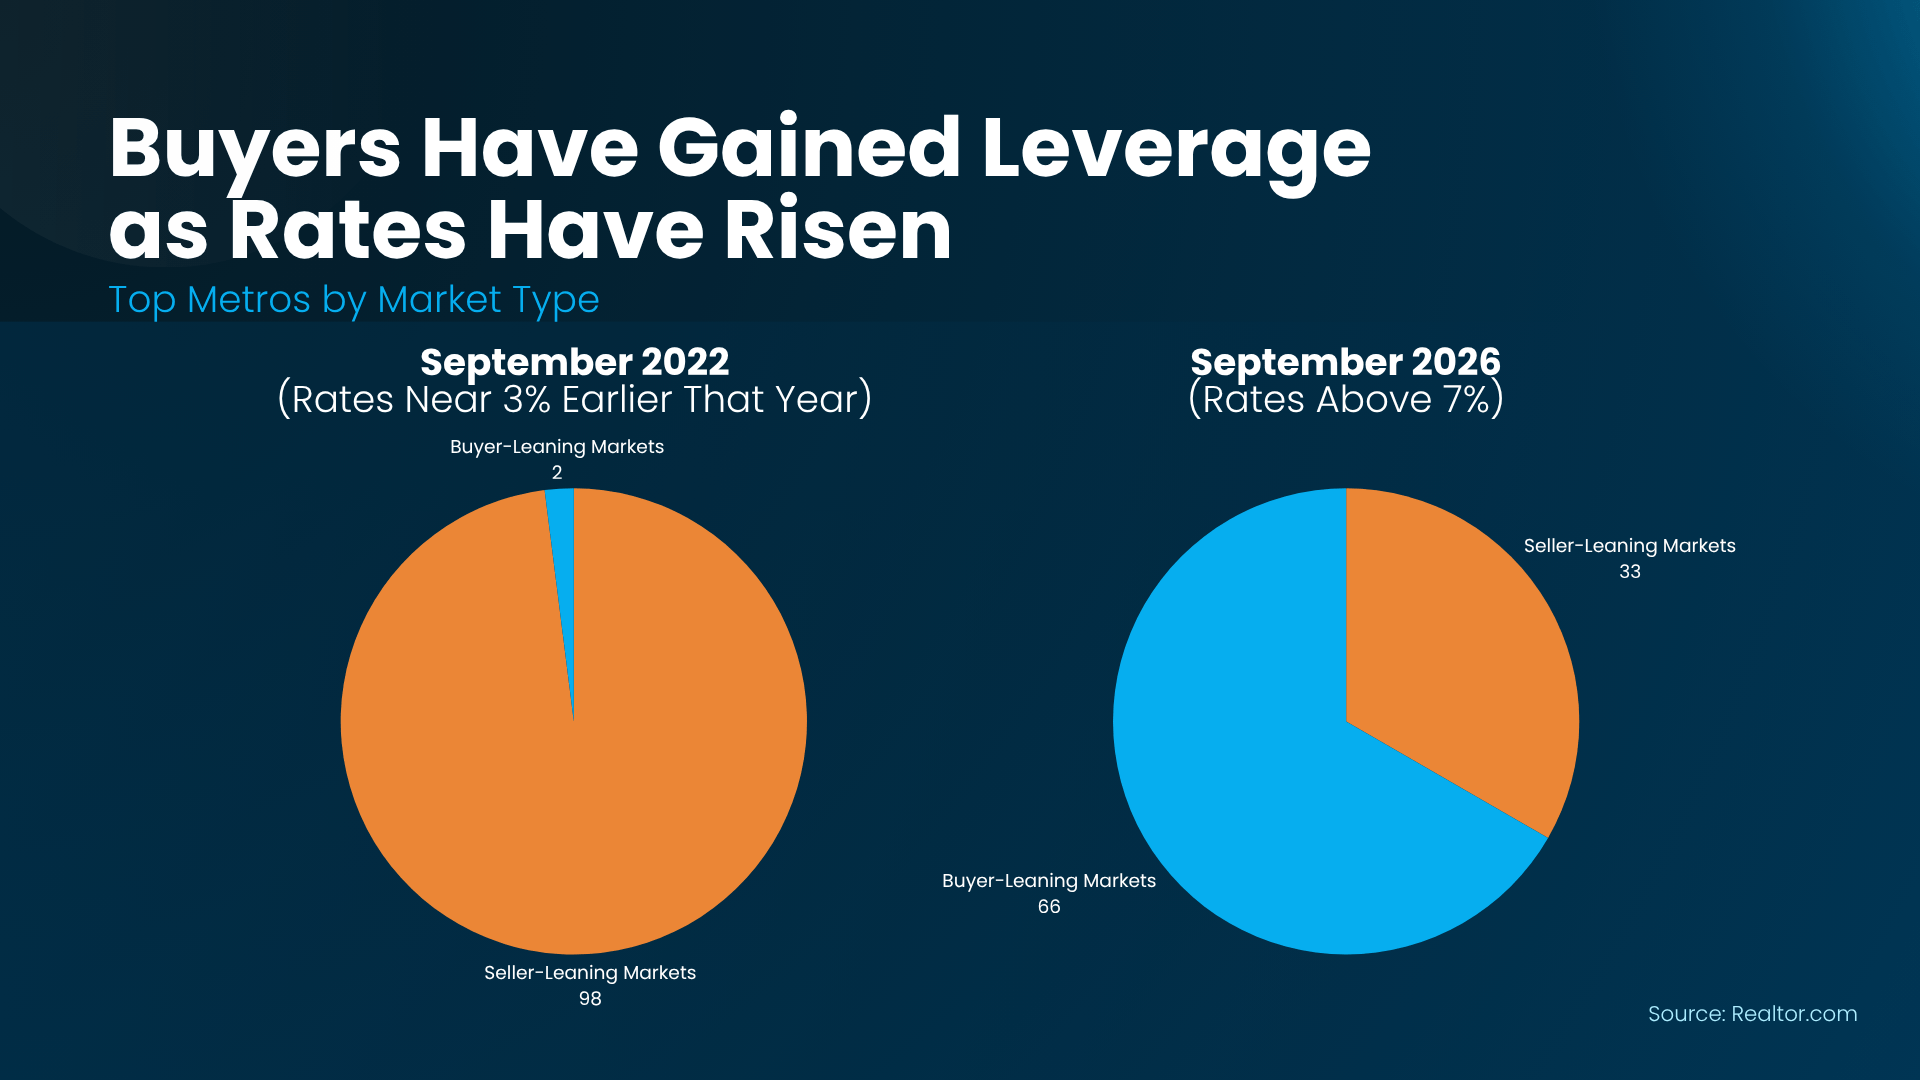
Mortgages, Refinance and Reverse Mortgages in The Villages, Florida

Helping Village Residents stay in their homes.

Simplifying Reverse Mortgage in The Villages, Florida

Speak to Bob Gersh now by calling: 352-561-3096 or
1-866-576-5254 ext. 700

Click Here To Set Up a Free Consultation.

  • Home
  • Myths
  • Questions
    • Are You Eligible?
    • Counseling
    • Moving Soon?
    • Use for the Money?
    • Live in your Own Home Forever.
    • Is a Reverse Mortgage right for you?
    • One time large expenses.
    • What kind of home do you own?
  • Reverse Mortgage Basics
    • The Villages, FL
  • Blog
  • About
  • Podcast
  • Local Resources
  • Platinum Years
  • Contact
  • Realtor Tools

Is a Reverse Mortgage Right for You? Learn More…

As more and more mortgage companies are "jumping on the bandwagon" offering reverse mortgages, here are two facts you should know:

  • Most companies who offer reverse mortgages simply broker or sell your loan to one or two of the large wholesalers.
  • Most companies offer similar products and programs.

What does that mean for you?

You should be looking for a reputable company who you can trust to give you professional advice on whether or not you are a good candidate for a reverse mortgage…not just whether or not you qualify. A reverse mortgage is an excellent program, but it's not right for everyone.

  • Senior Couple Meeting With Financial Advisor At Home
  • Senior man doing calculation at home
    Senior man busy doing calculation, counting money and bills at home, sitting at desk.
  • Miniature house over money isolated
    Miniature house over money isolated on white background
We will provide you with a free, no-obligation personalized Suitability Report that will help you determine not only if you qualify for a reverse mortgage...but if a reverse mortgage is a good option for you.

East Coast Capital is an organization of honest, ethical, knowledgeable professionals who will give you the straight answers. Reverse Mortgages are our business.

Call Bob Gersh Today 352-561-3096 or 1-866-576-5254 ext. 700

Company NMLS# 1810279

MLO Timothy Bradford NMLS 21031

Mortgage Lender License# MLDB8675 - dba Coast to Coast Capital Corp - Florida Office of Financial Regulation
Reverse Mortgage  The Villages FLReverse Mortgage  The Villages FLReverse Mortgage The Villages FLReverse Mortgage  The Villages FL

Get More Information About Reverse Mortgages

Fill out the form below to learn more about Reverse Mortgages offered by East Coast Capital.

  • I agree to be contacted by Robert D. Gersh, via call, email, and text for mortgage services. To opt out, you can reply "stop" at any time or reply "help" for assistance. You can also click the unsubscribe link in the emails. Message and data rates may apply. Message frequency may vary. https://askbobgersh.com/privacy-policy/

admin November 20, 2026

A Mortgage Rate Buydown Could Make Your Next Home More Affordable

A Mortgage Rate Buydown Could Make Your Next Home More Affordable

November 20, 2026·4 min read

You want to find the right home, but you also need the right monthly payment. And that can be hard when it feels like just about everything right now is putting a squeeze on your budget. 

But there’s a tool that can help, and many buyers have never heard of it – it’s called a rate buydown. Here are the basics.

What Is a Rate Buydown?

When you’re borrowing money to buy a home, it usually works like this. The higher your mortgage rate, the bigger your monthly payment. And with rates where they are now, some buyers are feeling the crunch. That’s where a buydown can really come in handy.

A buydown lets you pay some money upfront to get a lower mortgage rate – and by extension a better monthly payment. Basically, it’s a way to get a lower mortgage payment without waiting for mortgage rates to fall. 

There are two main types, and they work a little differently. 

Temporary Buydowns: Starting Smaller

A temporary buydown lowers your rate for a specific amount of time – usually the first one to three years. When the buydown period is up, you begin making the full payment amount. The loan’s official rate stays the same – you’re just getting help with part of the payment in the early years.

Think of it like a gift card for your mortgage. Money goes into an escrow account at closing. Each month, part of your payment comes out of that account instead of your pocket.

Here are the most common options when it comes to temporary buydowns:

  • 1-0 buydown: Your rate is 1% lower for the first year.
  •  2-1 buydown: Your rate is 2% lower the first year and 1% lower the second year.
  • 3-2-1 buydown: Your rate is 3% lower the first year, 2% lower the second, and 1% lower the third.

Permanent Buydowns: Lower Forever

A permanent buydown is a bit different. The big draw here is that they last for the entire loan, which could be 15 or 30 years – not just a couple of years like a temporary buydown. But normally, the monthly savings are smaller.

Here’s how this one works.

It’s paid for with points. Generally, one point equals 1% of your loan amount. And each point usually lowers your rate about a quarter of a percentage, but this differs from lender to lender. The important distinction? 

  • A temporary buydown gives you short-term payment relief. 
  • A permanent buydown can lower your payment for as long as you keep that mortgage.

Why Buydowns Are Worth Asking About Right Now

With more homes available for sale, more sellers and builders are offering incentives to attract buyers. Some are even willing to pay for your buydown. 

And whether that’s advertised up front or something you ask for in negotiations, it can have a bigger impact on your bottom line than you’d think. 

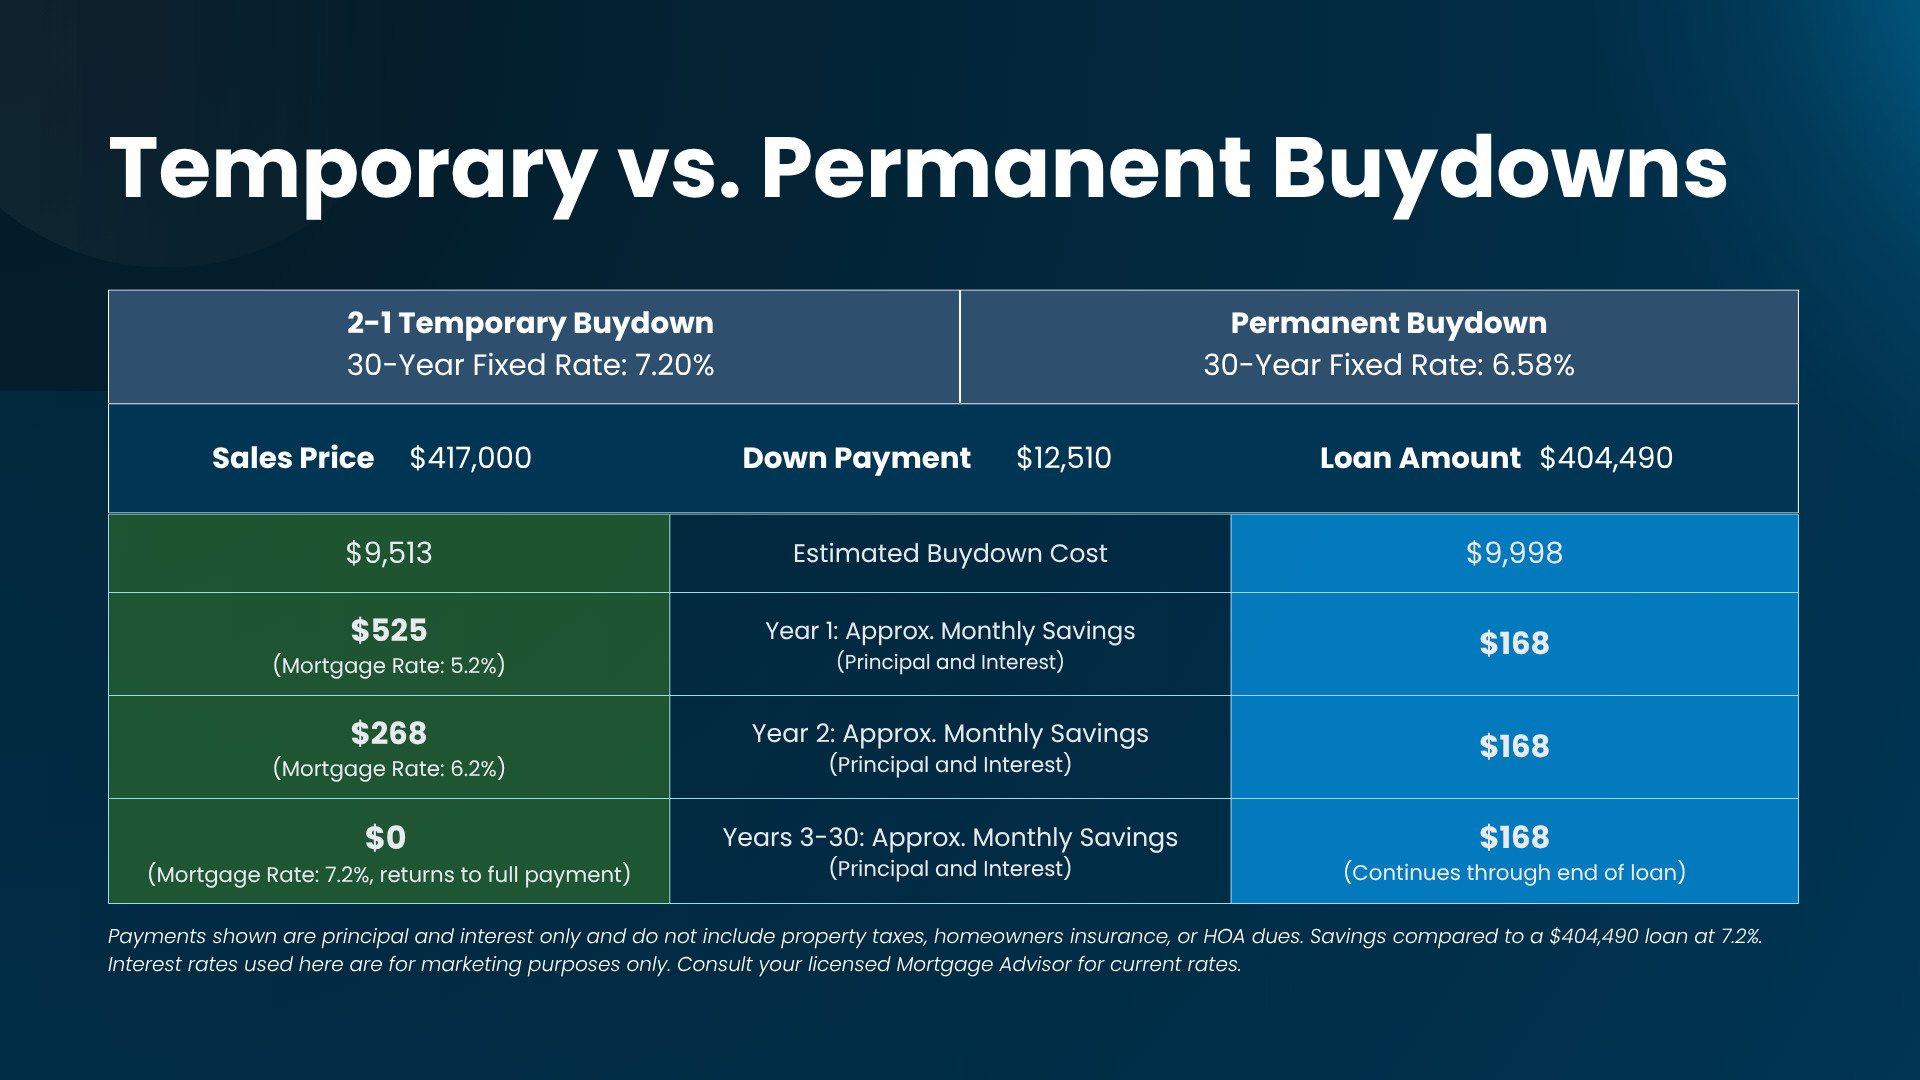
Take a look at this example comparing a seller-funded 2-1 buydown with a permanent buydown on a median-priced home. In this scenario, the seller would pay for the upfront buydown costs. Remember, these are estimates – your numbers will vary:
a blue and green chart with white text

In this example, the temporary buydown provides roughly $520 in monthly payment savings during the first year, compared with about $170 a month from a permanent buydown. 

That’s a big difference in the short term. But there’s an important tradeoff. 

As mentioned before, the temporary buydown savings don’t last forever. Once the buydown period ends, the full mortgage payment kicks in. That’s why it’s important to compare the numbers over time, not just during the first year. 

How To Know if a Buydown Makes Sense for You

This is where a lender can really help you explore your options. A buydown isn’t automatically the best choice for every buyer. It depends on your budget, how long you plan to stay in the home, and what you’re trying to accomplish.

A temporary buydown could give you extra room in your budget during the first couple of years, when you’re also managing moving expenses and settling into your new home. And if you expect your income to go up over time, this can be a good option.

On the flipside, a permanent buydown could make more sense if you plan to stay put for years and want the reassurance that the savings are sticking around until you move.

Either way, if you’re considering a buydown, the advice is simple. 

  • Make sure you can comfortably afford the full mortgage payment, even if you’re starting with a temporary reduction. 
  • Factor in what it could look like if the payment goes up after the buydown period ends. You want to be sure your budget can handle it. 
  • Remember, lenders check whether you can afford the full payment, not just the discounted amount. 

Bottom Line

If you’ve found a home you love but the monthly payment is giving you pause, talk to your agent about buydowns. Then, meet with your lender to see the real numbers for your situation.

A buydown could give you another way to make the numbers work, especially if a seller or builder is willing to help. Who knows it may just be the difference between  “maybe someday” and “welcome home.”
Filed Under: Reverse Mortgages

admin November 19, 2026

3 Things Sellers Need To Know About Pricing Today

3 Things Sellers Need To Know About Pricing Today

November 19, 2026·3 min read

If you’re getting ready to sell your house, you’ve probably heard how important it is to price it right. And that’s especially true right now. 

Today’s buyers have more homes to choose from and they’re feeling pinched by today’s mortgage rates. That makes them more selective. And that means having the right pricing strategy matters more than ever. 

That starts with understanding these three things. Because, with the right approach, you can still put your house in a great position to sell.

1. Price for Your Competition, Not Just the Comps

It’s natural to look at what your neighbor’s house sold for and think yours should sell for something similar. And those comparable sales (or comps) absolutely matter. But they only tell part of the story. Here’s why.

Buyers aren’t shopping against what sold three or even six months ago. They’re comparing your house to what’s available right now.

That’s why your agent will look at more than just recent sales. They’ll also consider the houses currently for sale, what’s going under contract, and how your house stacks up against those options to find the right price for your house. 

The goal isn’t necessarily to price lower than everyone else. It’s to make sure buyers see the value in choosing your house over the competition.

As Jake Krimmel, Senior Economist at Realtor.com explains:

“Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Understanding how your house compares to what’s available today can help you feel more confident in your asking price.

2. Buyers May Still Negotiate, Even When Your House Is Priced Right

Getting your asking price right puts you in a stronger position from the start. But when an offer comes in, remember that price is only one part of the equation. 

Today’s buyers may still negotiate on things like money toward closing costs or repairs, even when a house is priced well – and that’s not necessarily a commentary on your price, it’s just the norm for negotiation in today’s market. 

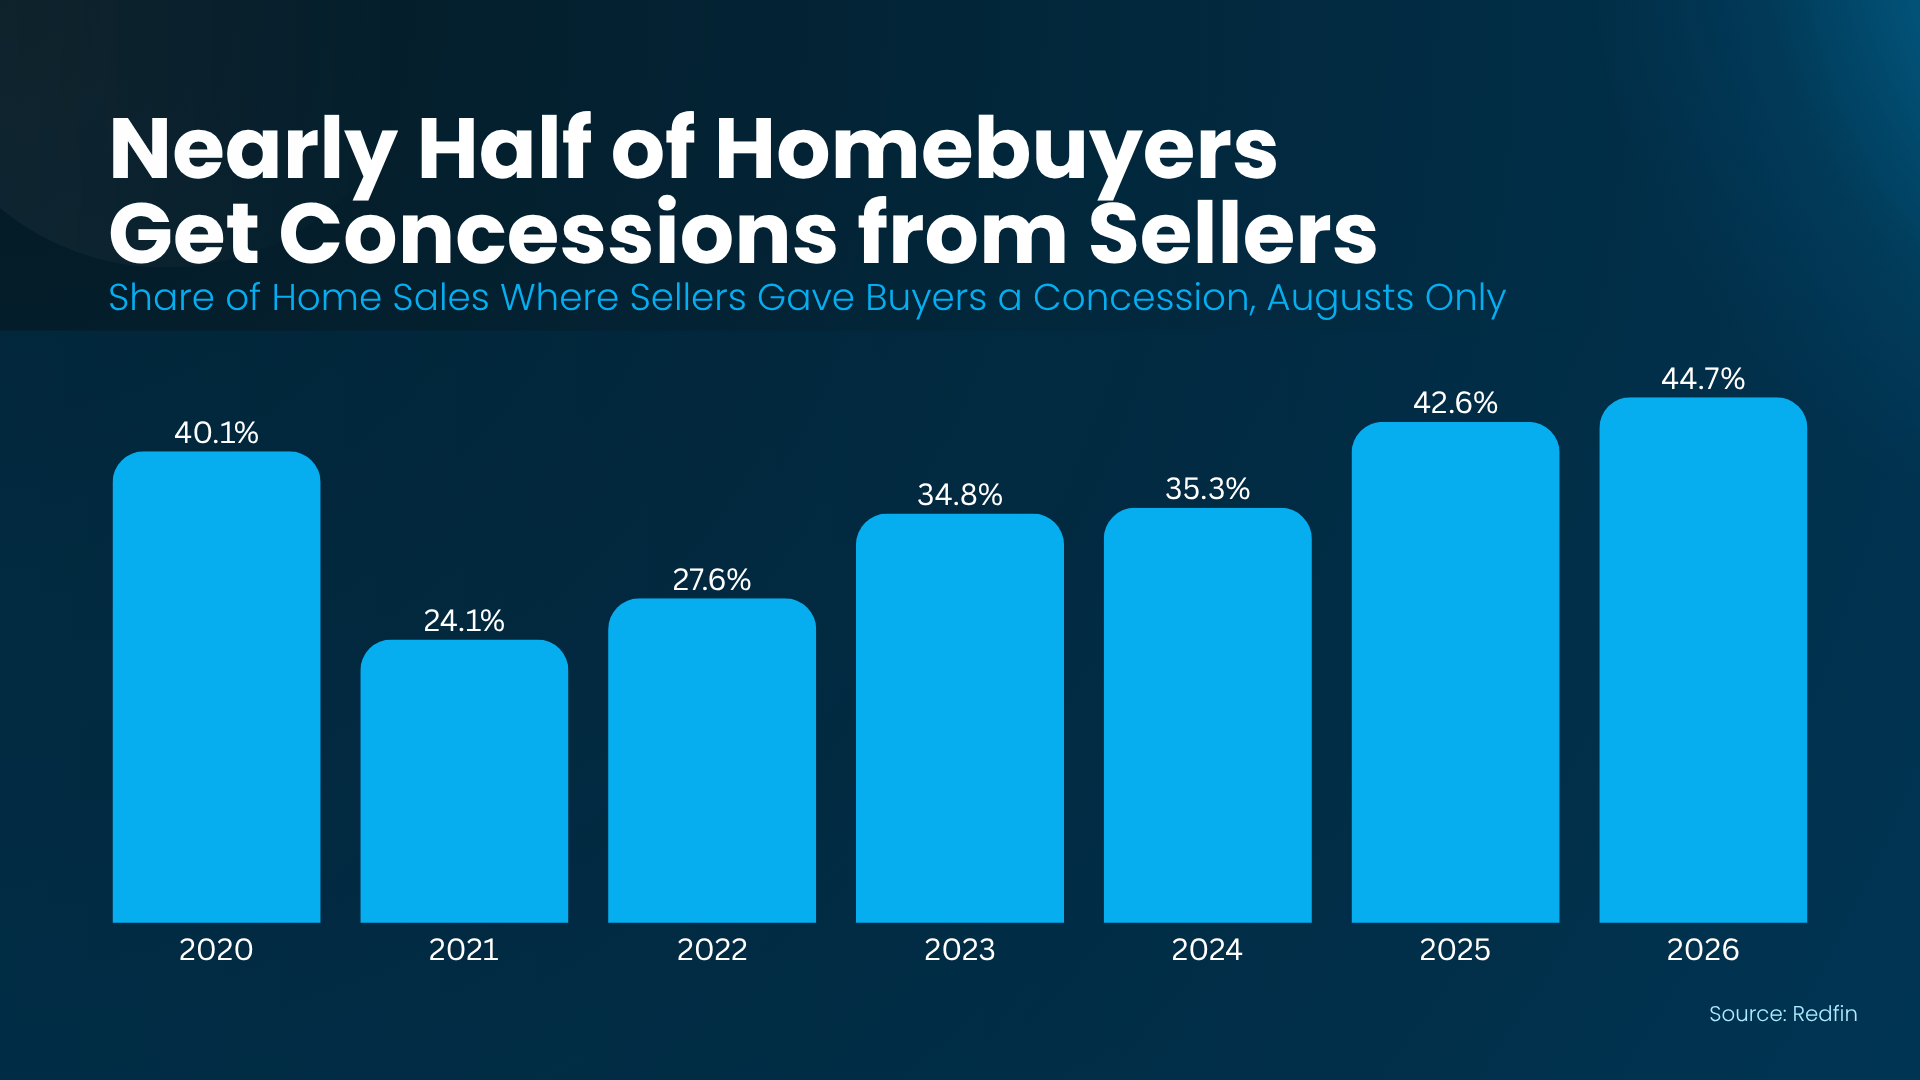
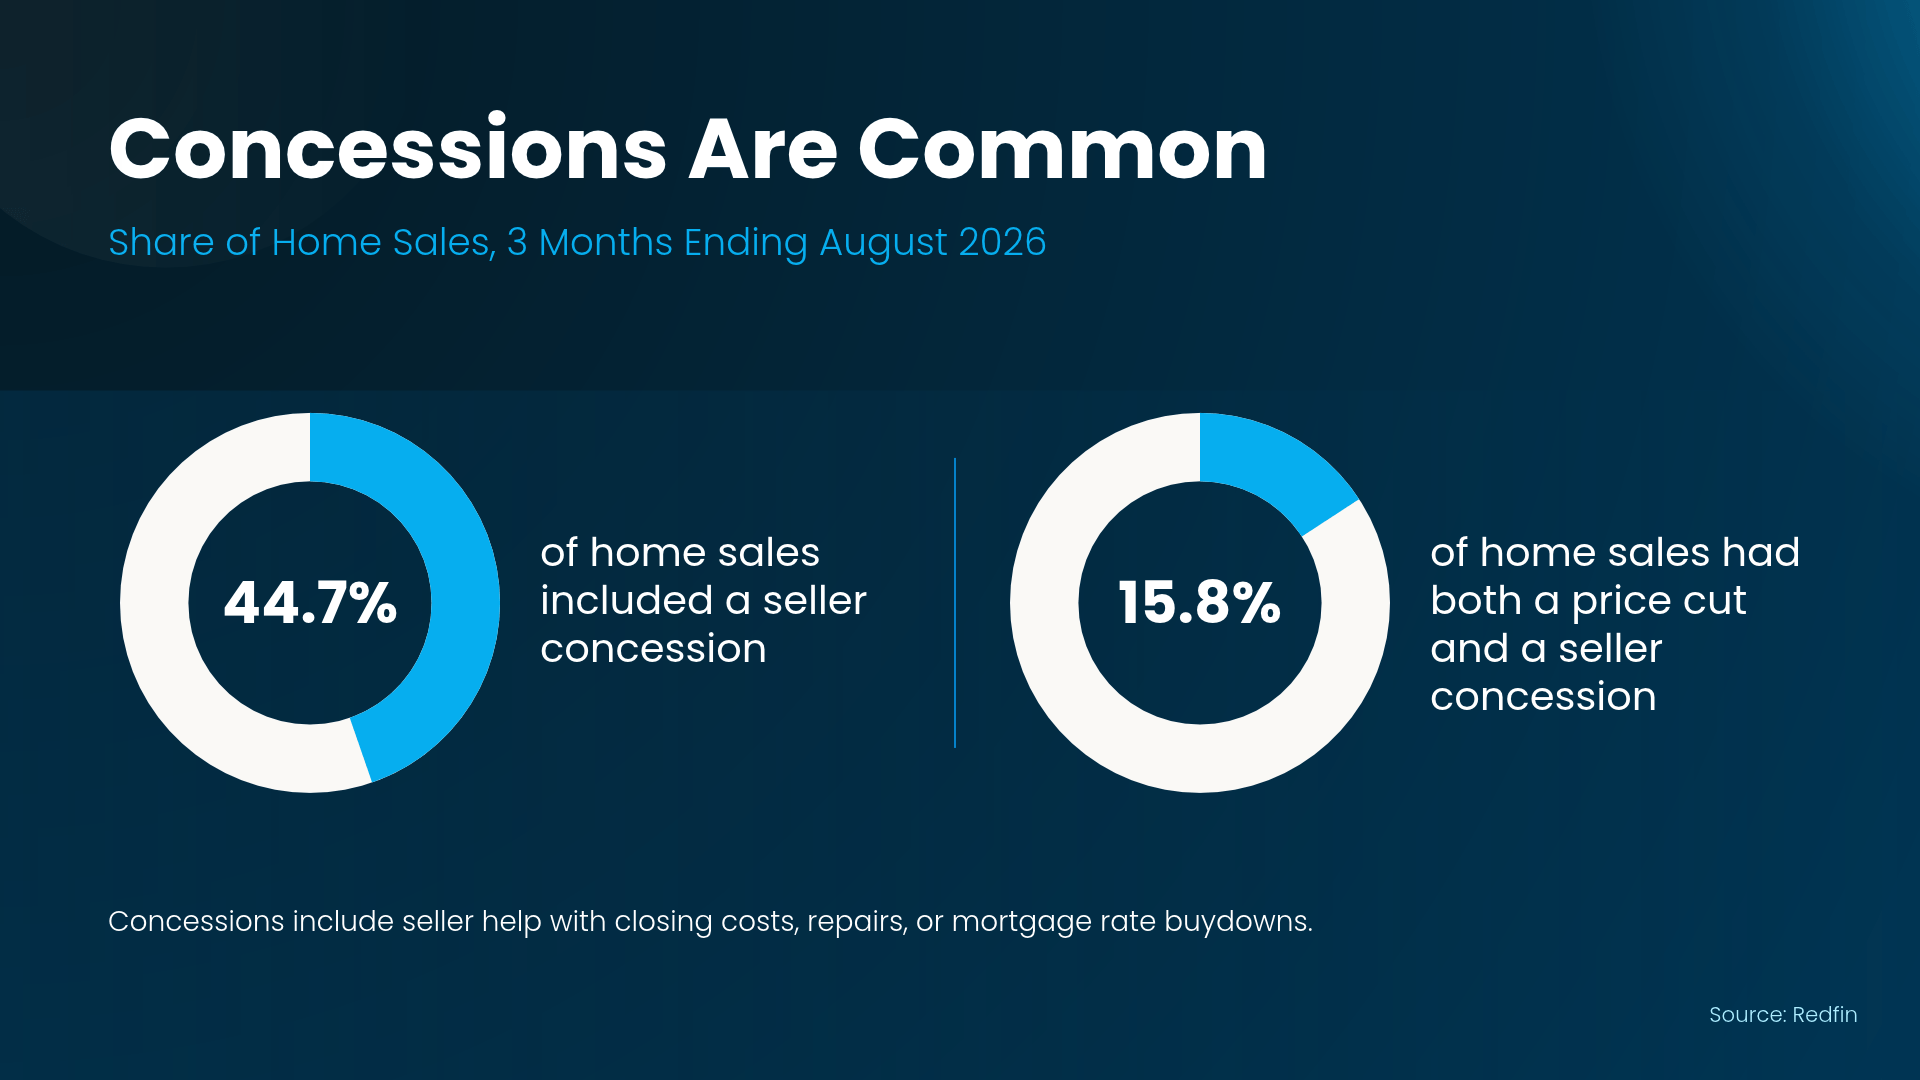
According to Redfin, 44.7% of home sales involve seller concessions. That’s just under half. And 15.8% had both a price reduction and a concession.

a blue and white pie chart

Now, that doesn’t mean you have to agree to everything a buyer asks for. But sometimes offering a closing-cost credit or helping with a mortgage rate buydown could be what seals the deal. Other times, holding firm is the better move. Your agent will help you decide.

The best advice? Look at the whole offer, including what you’ll actually walk away with, to decide what’s right for you.

3. Know When To Adjust Your Strategy

Even with a competitive price, some houses take longer to sell than others. And if yours isn’t getting the attention or offers you expected, that doesn’t mean your sale is off track. It just means it’s time to take a closer look at what’s happening.

Your agent can help you use buyer feedback and local market activity to figure out what adjustments, if any, could make a difference. 

  • Are buyers seeing your listing online but not scheduling showings? Maybe the photos or presentation aren’t doing your house justice.
  • Are people touring but not making offers? It could be the condition, the price, or how your house compares to others they’ve seen.
  • And if buyers are making offers, but the terms aren’t working for you, that may call for a different negotiation strategy altogether.

While you may worry that means you have to drop your price, that’s not always true. A price cut can help, but only if it addresses what’s keeping buyers from making a move. 

That’s why feedback, local competition, and an agent who knows how to interpret both are so important.

Bottom Line

Selling successfully today isn’t about finding one magic number and hoping everything falls into place. It’s about starting with a competitive price, understanding what buyers expect, and being willing to adjust your strategy when needed.

Want to know what it’ll take to sell your house in today’s market? Let’s look at the competition, talk through your options, and build a pricing strategy that works for you.

Filed Under: Reverse Mortgages

admin November 18, 2026

3 Housing Questions That Might Come Up at Your Next Family Dinner

3 Housing Questions That Might Come Up at Your Next Family Dinner

November 18, 2026·3 min read

This time of year usually means more time spent with family and friends. And in recent years, when everyone gets together, the conversation has a way of drifting to housing.

Your uncle is sure home prices are about to crash. Your cousin heard foreclosures are surging. And someone across the table brings up the word “recession.”

If you’ve wondered about any of this yourself, that makes sense. There’s a lot of noise out there. So let’s look at what the data actually shows, so you’ll have real answers the next time it comes up.

“Are Home Prices Going To Crash?”

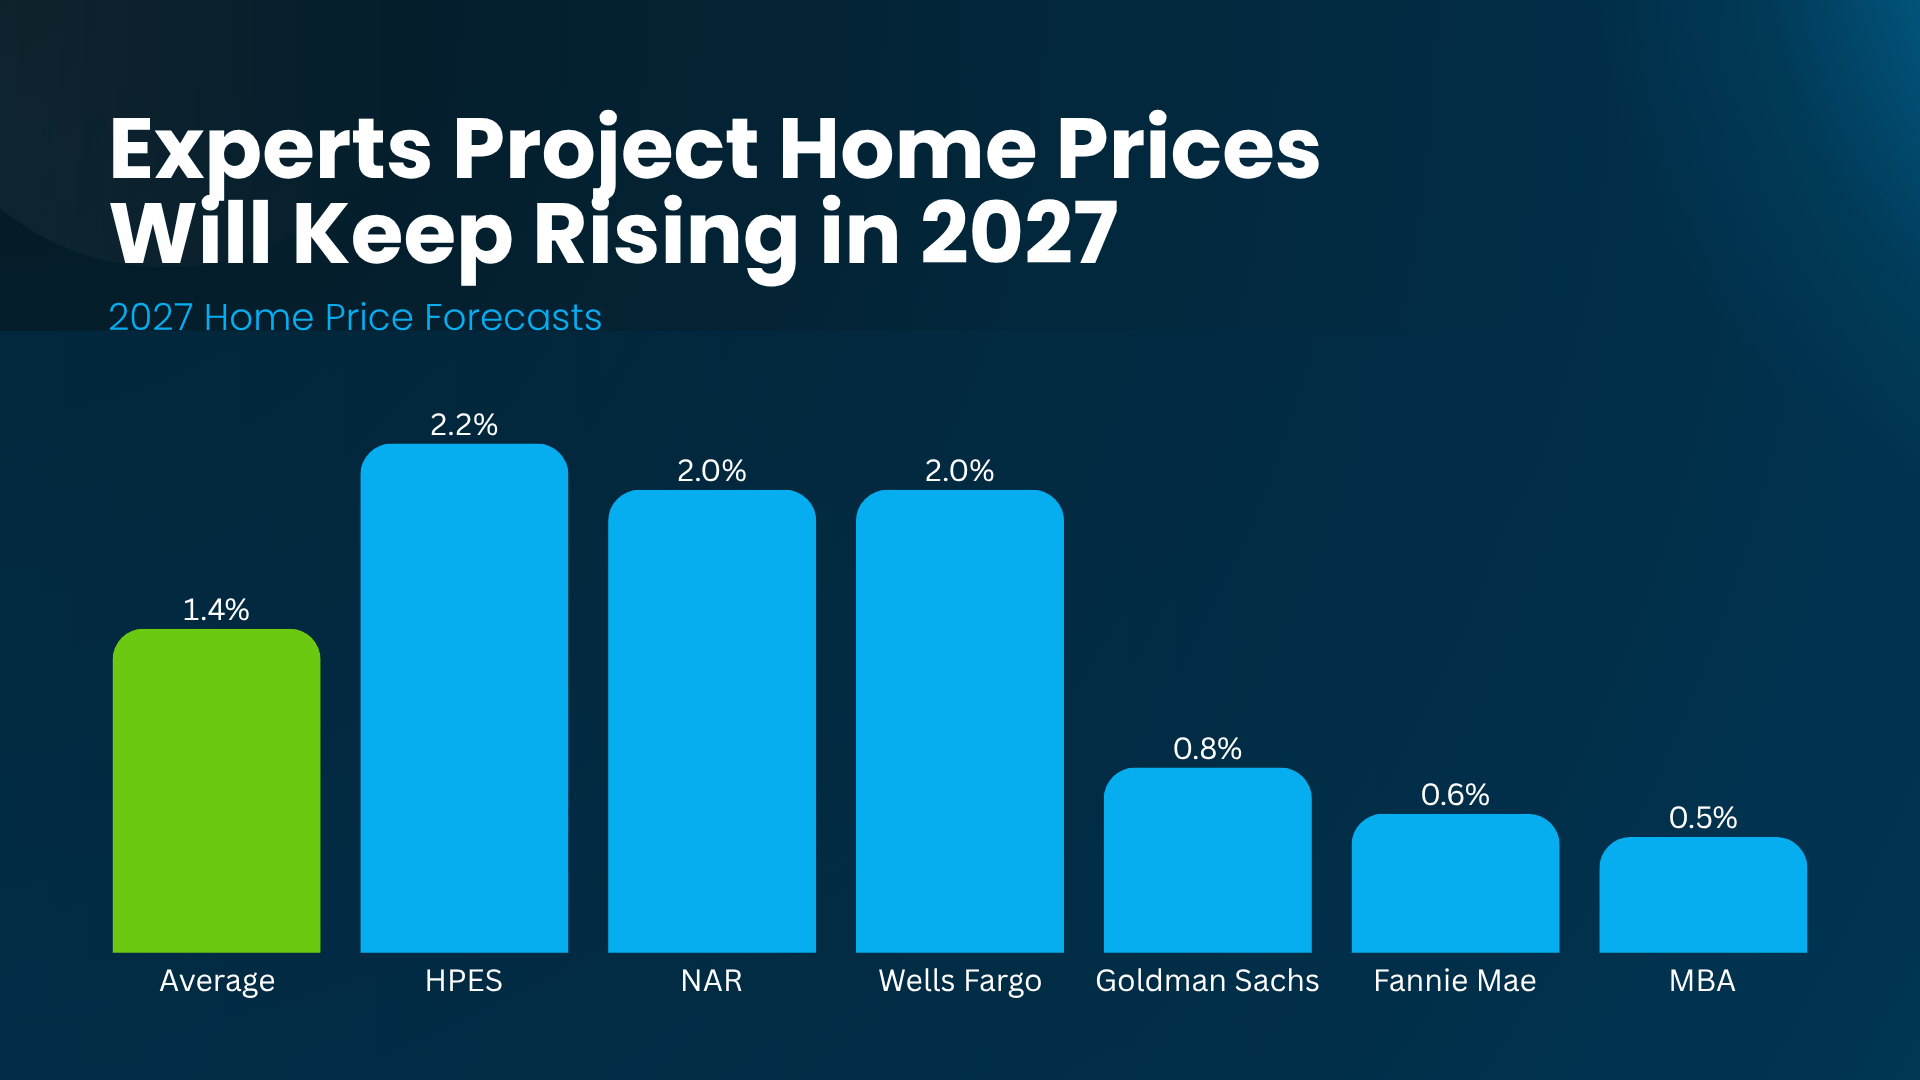
Let’s start with your uncle’s crash prediction. The short answer is no. Experts project home prices will keep climbing nationally in 2027. 

On average, forecasters expect prices to rise about 1.4% next year (see graph below). That’s slower than the big jumps of a few years ago, but it’s still growth, not a crash.

a graph of blue rectangles with white text

Prices are dipping in some markets, though. It just depends on where you live. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains why:

“Price declines are occurring mainly in southern states, where there has been robust new home construction in recent years. Given the region’s faster job growth, these price drops should be viewed as temporary and as a second-chance opportunity for those previously priced out of the market.”

So, the dips that are fueling all the social media chatter are limited to select areas, and experts think they’ll be short-lived. It doesn’t mean a crash is looming. 

If you’re thinking about moving, look at the numbers for your area.

“Is This 2008 All Over Again?”

Then your cousin chimes in about foreclosures. They’ve ticked up lately, but here’s some important context. That’s compared to very low levels. They’re still below where they were before the pandemic, according to ATTOM.

So, why doesn’t today look like 2008? Logan Mohtashami, Lead Analyst at HousingWire, explains:

“. . . we have had many recessions post-WWII but only one foreclosure crisis. That foreclosure crisis started with a massive credit boom from 2002-2005, and then a credit bust. . . none of that is happening now . . .“

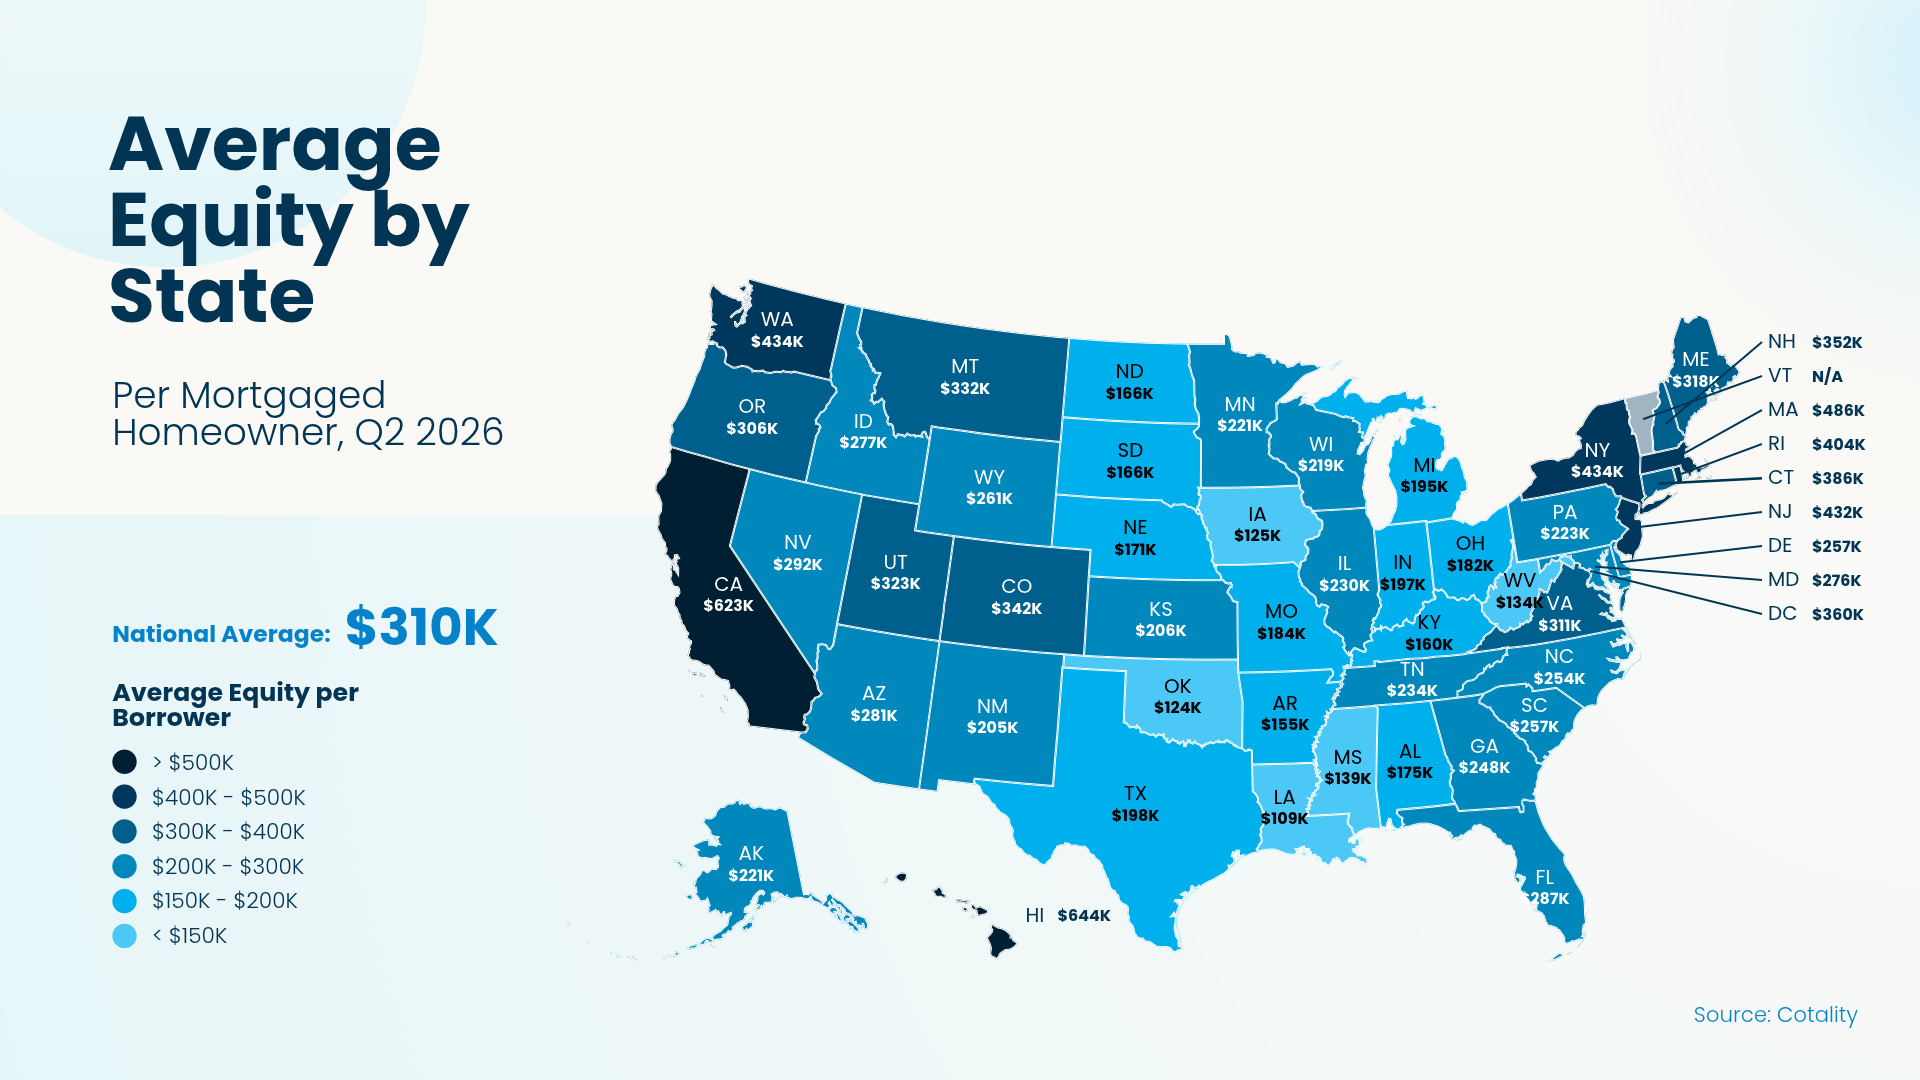
Today’s homeowners also have something a lot of people didn’t have back then – equity. In every state, the average homeowner with a mortgage has more than $100,000 of it, according to Cotality (see map below):

a map of the united states

If a homeowner hits a rough patch, they can usually sell their house instead of facing foreclosure.

“Are We Headed for a Recession?”

While someone in your family may be convinced a recession is coming, experts don’t agree. The average forecast from The Wall Street Journal’s survey of economists puts the odds at about 24%, so most experts aren’t expecting one. And that’s a good thing.

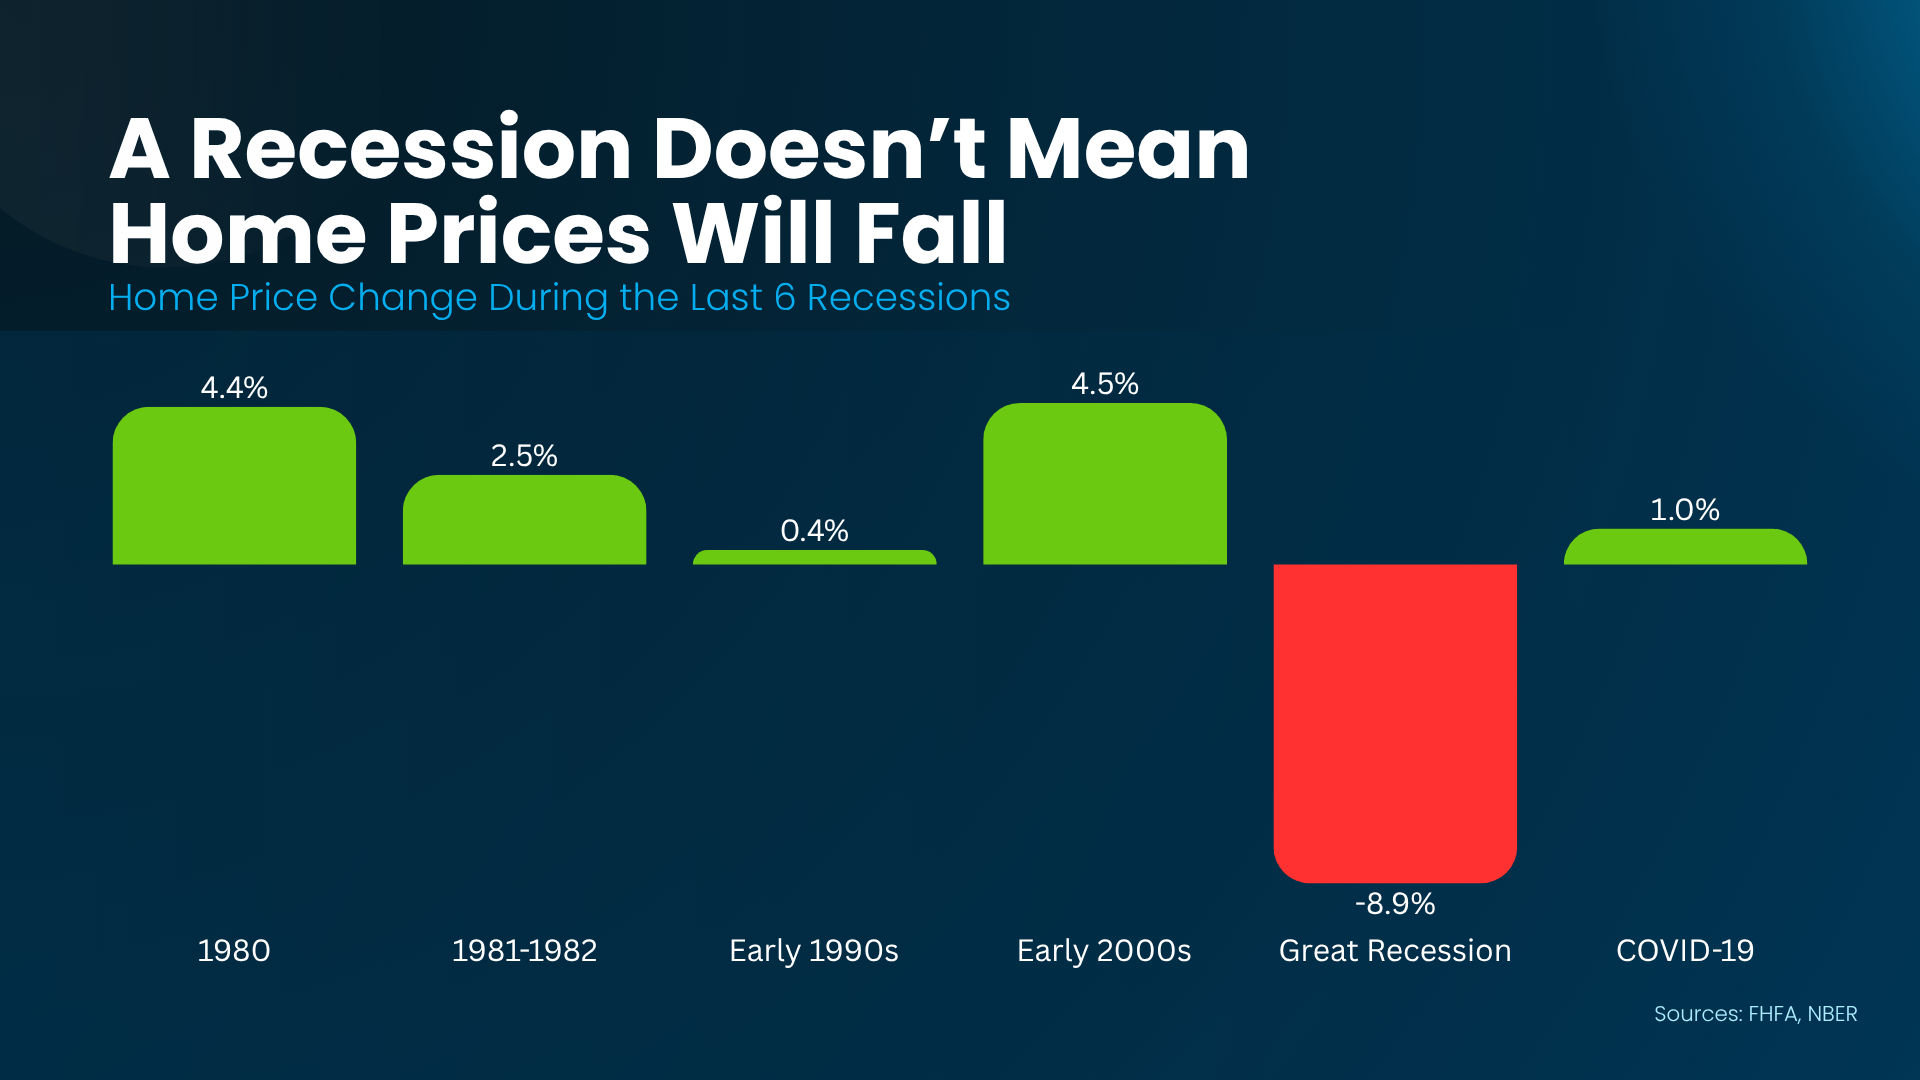
But even if one hits, history shows a recession doesn’t mean home prices will automatically fall. In 5 of the last 6 recessions, prices actually went up, according to the Federal Housing Finance Agency (FHFA) (see graph below):

a graph of a graph showing the price of a fall

The one exception was 2008, the only one of these recessions that started in the housing market itself.

Bottom Line

So, the next time your uncle predicts a crash or your cousin brings up 2008, you’ll know prices aren’t crashing, foreclosures are still low, and a recession doesn’t automatically spell trouble for housing. 

If a move in 2027 is on your mind, let’s look at what prices are doing in your neighborhood so you can plan with real local numbers, not scary headlines.

Filed Under: Reverse Mortgages

admin November 17, 2026

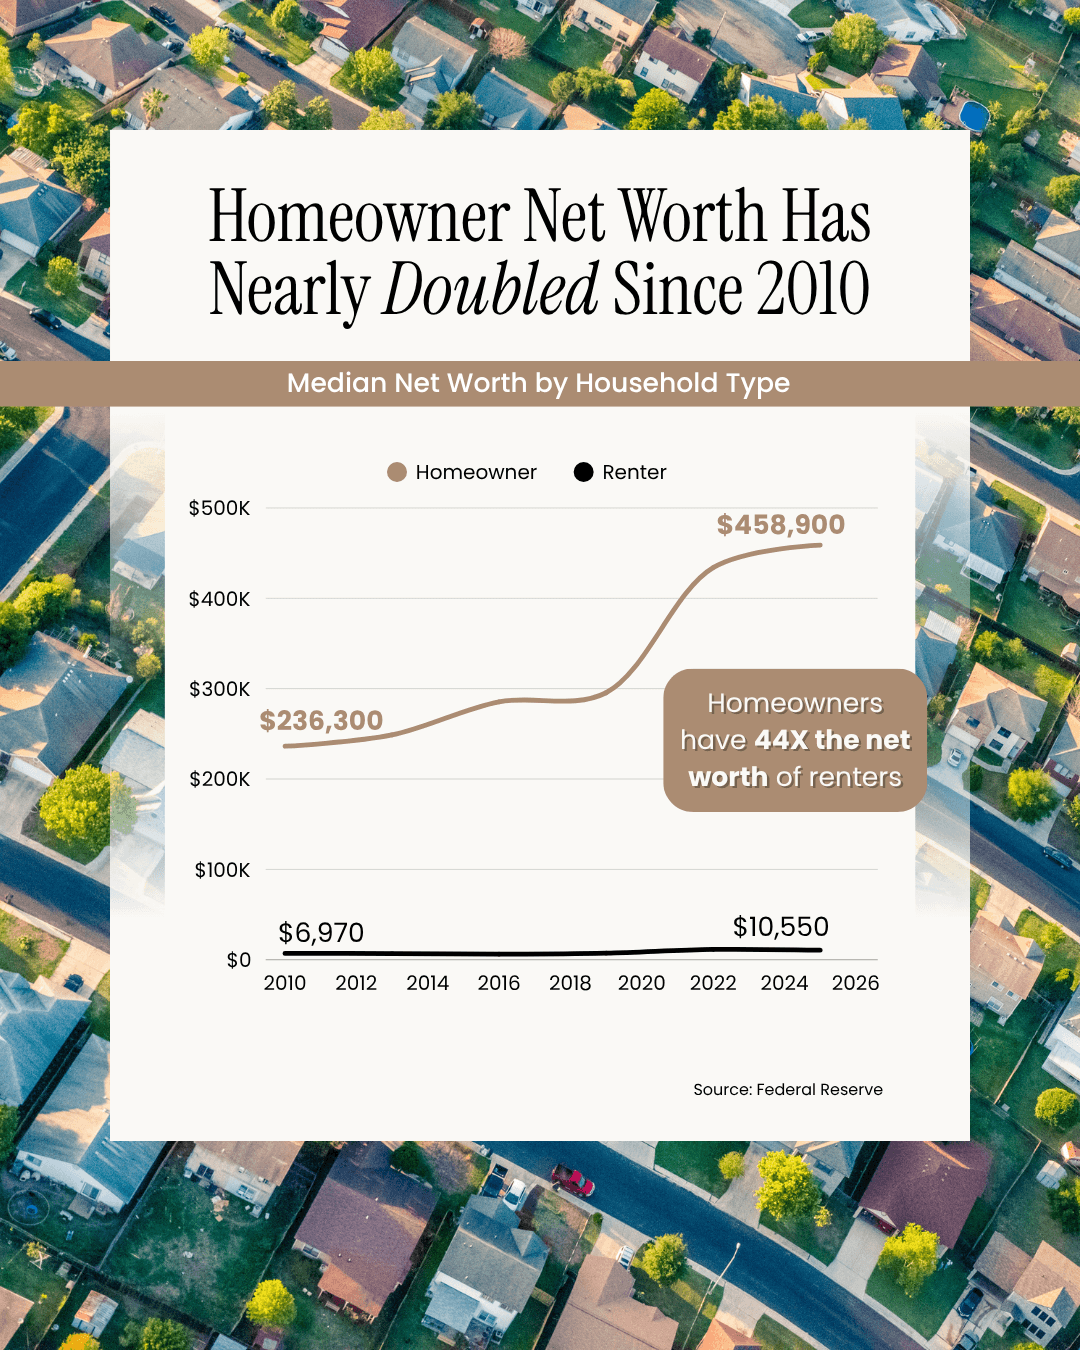
Homeowner Net Worth Has Nearly Doubled Since 2010

Filed Under: Reverse Mortgages

admin November 16, 2026

A Fixer-Upper Could Be Your Path To Homeownership

A Fixer-Upper Could Be Your Path To Homeownership

November 16, 2026·3 min read

When the homes you love keep landing outside your budget, it may be time to look at the ones other buyers skip.

A fixer-upper won’t be the right call for everyone. Plenty of buyers want a home that’s ready on move-in day. But homes that need some updating could get you in the door for a lot less. 

More buyers are starting to realize it too. And Danielle Hale, Chief Economist at Realtor.com, explains why:

“Fixer-uppers give buyers a way to break into the housing market at a time when affordability is still stretched thin. For those with the vision. . . fixer-uppers provide both a starting point in the market and the chance to create a home that’s truly their own.”

If that sounds like you, here’s why a fixer-upper could be worth a closer look.

The Price Tag Is Usually Lower

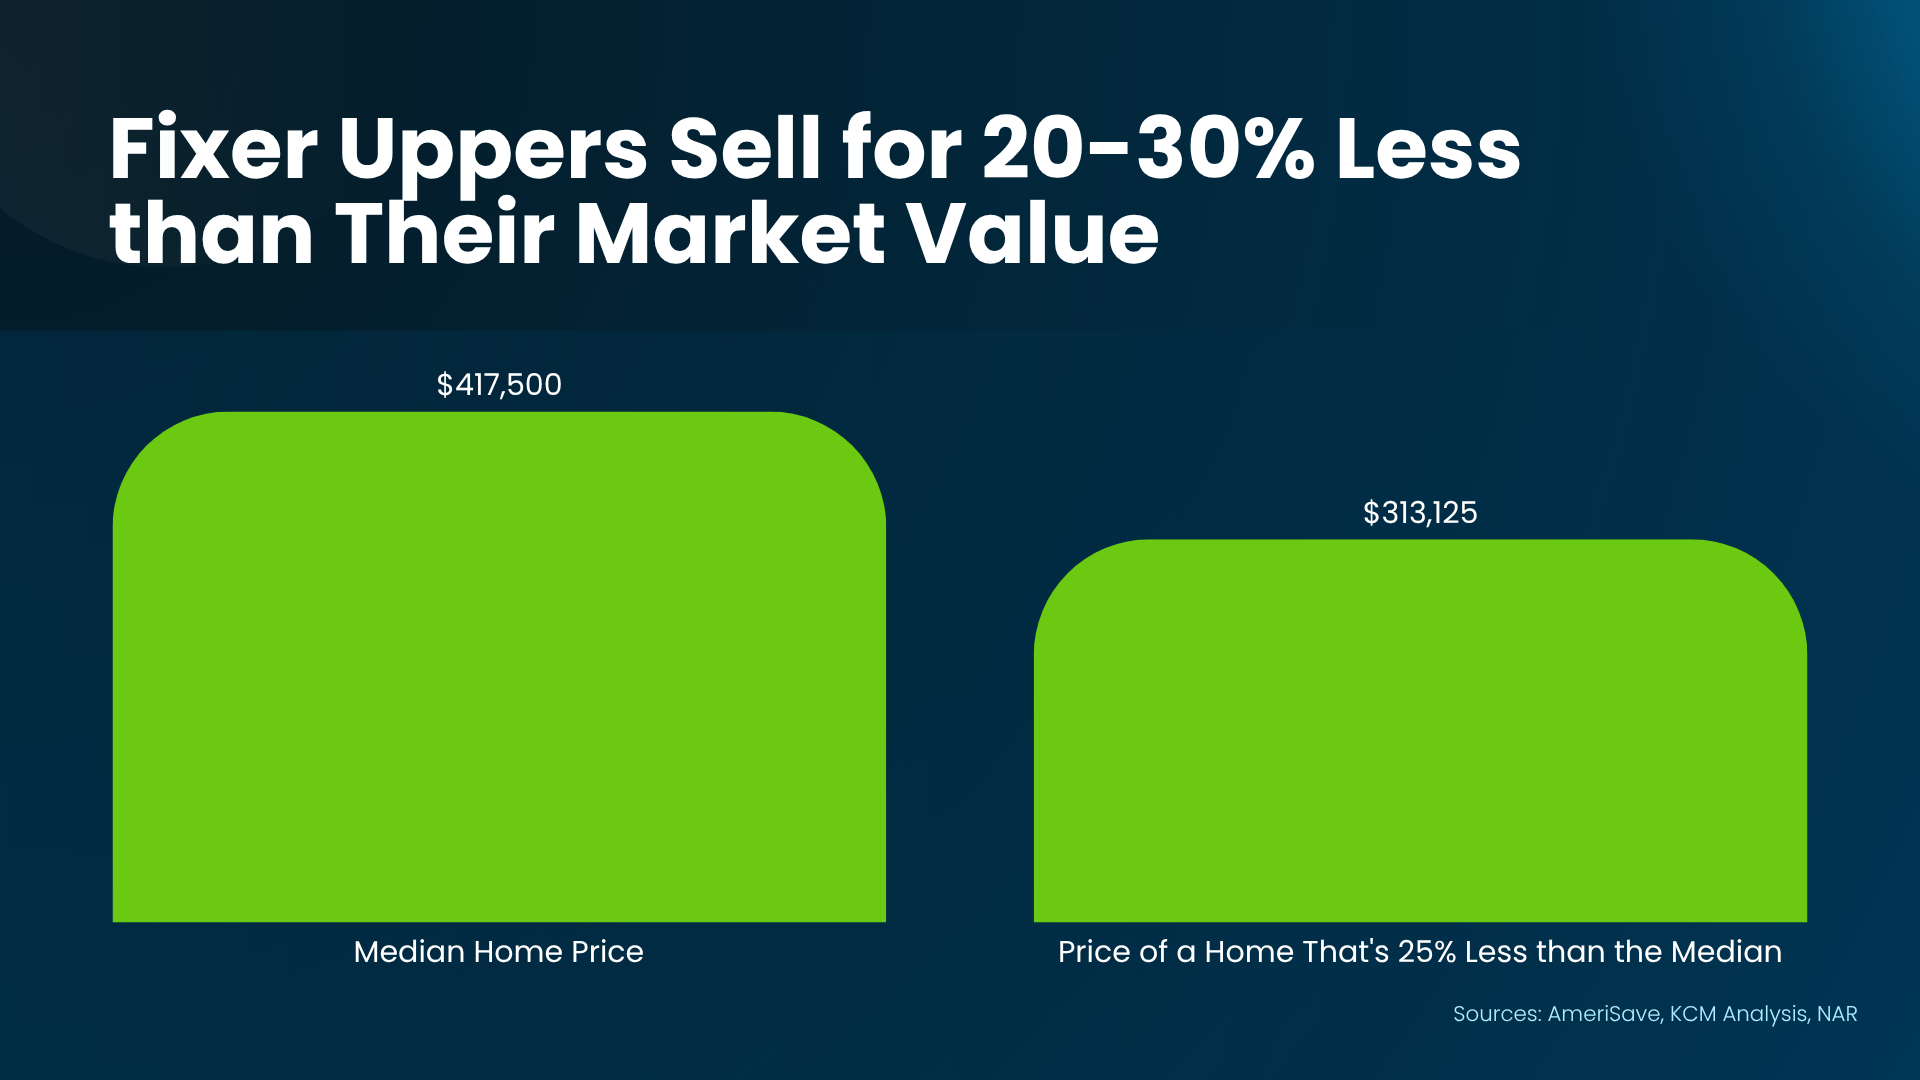
Because these homes need work, they tend to have a lower asking price up front. According to AmeriSave, fixer-uppers usually sell for 20% to 30% less than what they’re worth on the market.

Here’s what that could look like. KCM applied a 25% discount – the middle of that range – to the median home price from the National Association of Realtors (NAR). This is an example, not the average price of a fixer-upper. But it shows the savings could top $100,000 (see graph below):

a green rectangles with white text

That’s a big difference up front and it could be what gets you into a home today. And odds are you don’t have to tackle all the repairs at once – you can space them out over time as it works for you.

Just remember repair costs can add up quickly and eat into those savings if you don’t plan ahead. So, before you make an offer, get estimates from a contractor and set a repair budget you’re comfortable with. There are even some loan types designed to help pay for the work.

One Loan Can Cover the Home and the Repairs

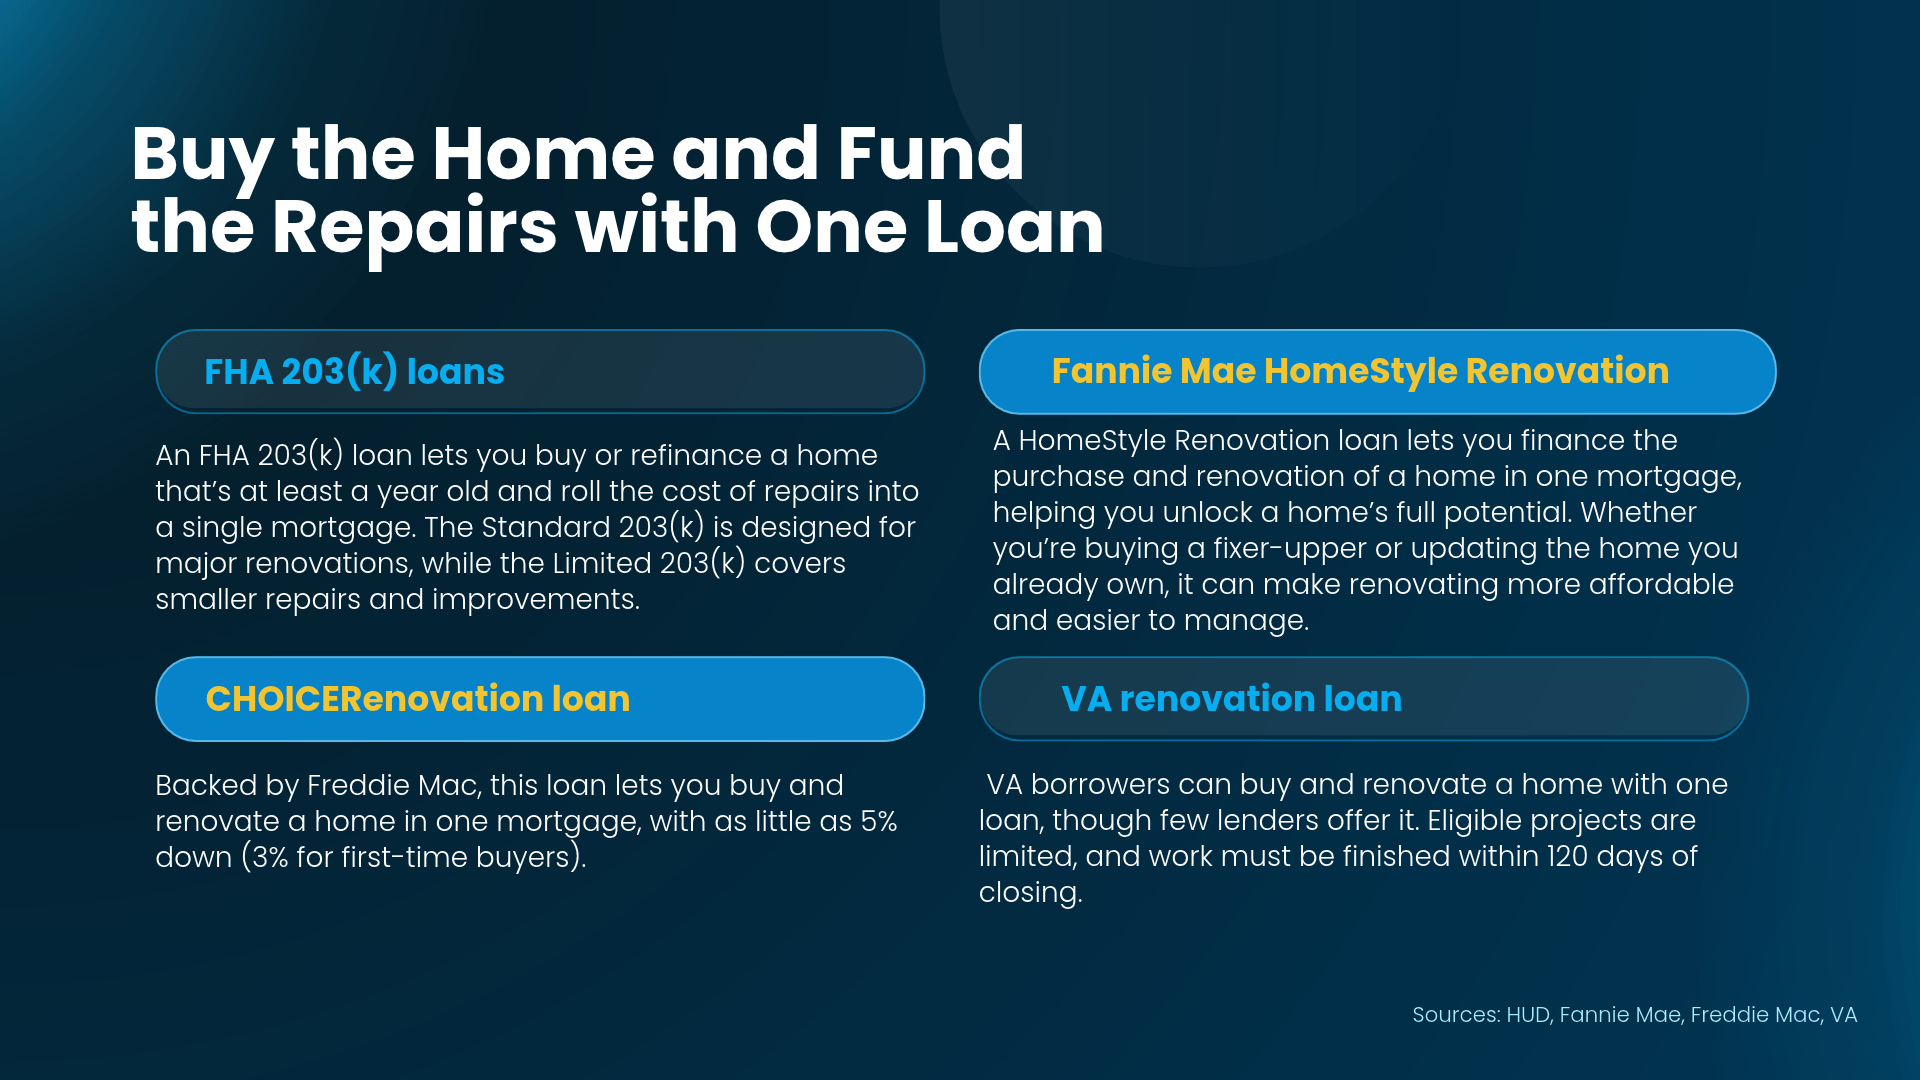
With a renovation loan, you can roll the cost of the work into your mortgage, so you don’t have to cover it all out of pocket once you move in. Here are a few options from FHA, Fannie Mae, Freddie Mac, and the VA (see visual below):

a screenshot of a home loan application

Each program has its own rules, and not every lender offers all of them. So, talk to a trusted lender to see which options are available to you and which make sense for how you plan to tackle updates and repairs over time.

Don’t Overlook Local Perks

Some cities even offer tax breaks to buyers who renovate a fixer-upper and raise its value. These programs vary by location, so check with your city or a tax professional to see what’s available where you want to live.

If you want to check for more information yourself, go to your local county or city official dot-gov website. Then, use the search bar and look for: [City or County Name] AND “home rehabilitation” OR “property tax incentive” OR “housing repair”

A local agent can also help you find fixer-uppers in the neighborhoods you have your heart set on.

Bottom Line

If move-in-ready homes keep coming in over budget, a home that needs some TLC could be your way in. Plan your repair budget and line up the right loan before you buy, and you can get in the door now and make the space your own over time, as your budget allows.

Let’s connect so you can start looking at fixer-uppers in the neighborhoods you love.

Filed Under: Reverse Mortgages

admin November 13, 2026

Planning To Sell in 2027? Start Prepping Now.

Planning To Sell in 2027? Start Prepping Now.

November 13, 2026·3 min read

If selling your house is on your calendar for 2027, you may be thinking you’ve got plenty of time. Maybe you’re aiming for January. Maybe you’re waiting for spring. Either way, next year probably feels far enough away that getting ready can wait, too. 

But waiting until 2027 to sell doesn’t mean waiting until 2027 to get started.

Today’s buyers have more homes to choose from than they’ve had in years. So, if you want your house to stand out when it’s time to list, a little preparation now can make a big difference later.

How Early Should You Start Getting Ready?

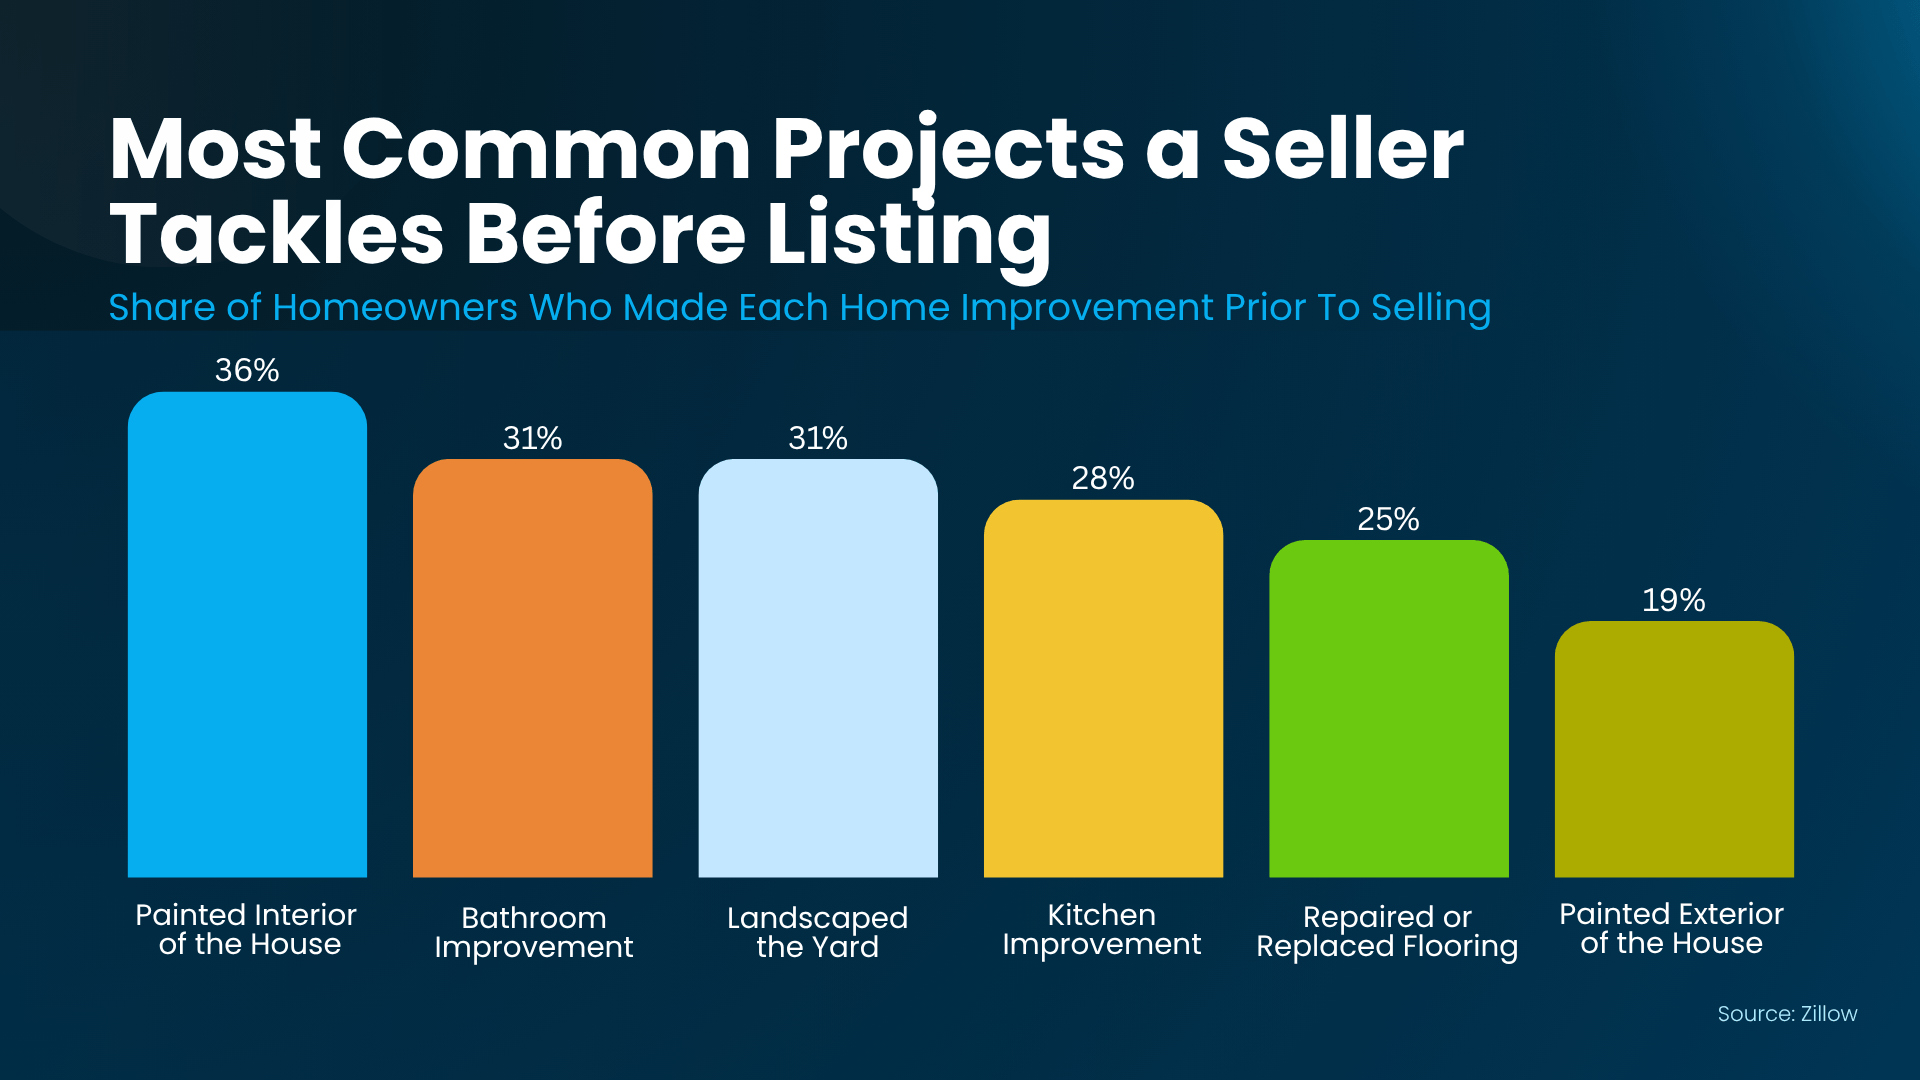
As a general rule of thumb, Zillow recommends giving yourself about 2-3 months to get your house ready to list. And that makes sense when you consider that the vast majority of sellers (78%) did at least one home improvement project before their house hit the market. 

That gives you plenty of time to decide what to fix, find contractors, get on their schedules, actually make the updates, and get everything ready for photos and showings. 

But don’t worry – that doesn’t mean every seller had some big to-do. The most common? Interior painting (see graph below):

a graph of a number of colored rectangles

That certainly doesn’t mean you need to tackle everything on this list. You may not need to do any of it. But odds are there’s at least one project you’ll want to do. And starting that conversation now gives you a leg up before next year. 

Here’s how to tackle it.

1. Talk to an Agent Before Starting Any Projects

While you might have a long list of things you think need updating, that doesn’t mean they’re all worth the time, effort, or money. 

An agent will help you figure out which projects deserve a spot on your to-do list based on what buyers want most and what other sellers are doing. That way, you’re not investing in updates that won’t make much of a difference when you sell.

2. Get Ahead with a Pre-Listing Inspection

One thing your agent may recommend today is that you go ahead and get a pre-listing inspection. It’s basically your cheatsheet to what a buyer’s inspection may turn up later on. 

And now that buyers have more options, they’re pickier – and you don’t want anything popping up in an inspection that could put them off.

For example, you know that HVAC system you’ve been hoping will make it through one more season? Now’s a good time to give it some attention – along with anything else you know needs a little TLC. That way a repair you could’ve handled months ago won’t become a surprise in the middle of your sale. 

According to Angi, a pre-listing inspection typically costs $300-600 and that can be money well spent. As the National Association of Realtors (NAR) explains:

“An inspector will be able to give you a good indication of the trouble areas that will stand out to potential buyers, and you’ll be able to make repairs before open houses begin.”

The advantage isn’t just knowing what may come up, but being able to get ahead of it and space out the projects on your own schedule. So you don’t feel stressed during go-time. 

3. Save the Final Touches for Closer to Listing Day

But remember, not everything needs to happen right away. Some things are better saved for when you’re closer to listing.

Think deep cleaning, staging, touching up paint, and tidying up the landscaping. Those are the finishing touches that’ll help your house look its best when buyers walk through the door.

But there’s one thing you can start anytime: decluttering. Go ahead and tackle the closets, garage, or storage room you’ve been avoiding. Future you will appreciate having a few less boxes to pack.

The idea isn’t to get everything done today. It’s to spread the work out so you’re not scrambling when listing day arrives. As Redfin puts it:

“Smart preparation leads to a smoother sale, stronger offers, and fewer surprises during closing. . . Homes that are clean, well-staged, priced right, and professionally photographed tend to sell quickly.”

Bottom Line

You don’t need to spend the rest of the year renovating your house or packing up your life. But you can start making a plan.

The earlier you figure out what needs to be done, the more time you’ll have to do it right. And that means less rushing, fewer last-minute surprises, and a better chance to make a great first impression when you’re ready to sell.

Thinking about selling in 2027? Let’s talk about what your house needs, what it doesn’t, and how to get everything ready on your timeline.

Filed Under: Reverse Mortgages

admin November 12, 2026

The Housing Market Is on Solid Ground, Even with More Foreclosures

The Housing Market Is on Solid Ground, Even with More Foreclosures

November 12, 2026·3 min read

It’s been nearly two decades since the 2008 housing crash, but the word “foreclosure” can still make people uneasy. And if you’re planning a move, you may be wondering if more foreclosures will flood the market with homes for sale – especially if you’ve seen the headlines lately.

Buyers may be hoping for a rush of bargains. Sellers may be bracing for more competition. The latest data points to neither, and knowing why can help you plan your next move with confidence.

A Modest Rise from a Low Starting Point

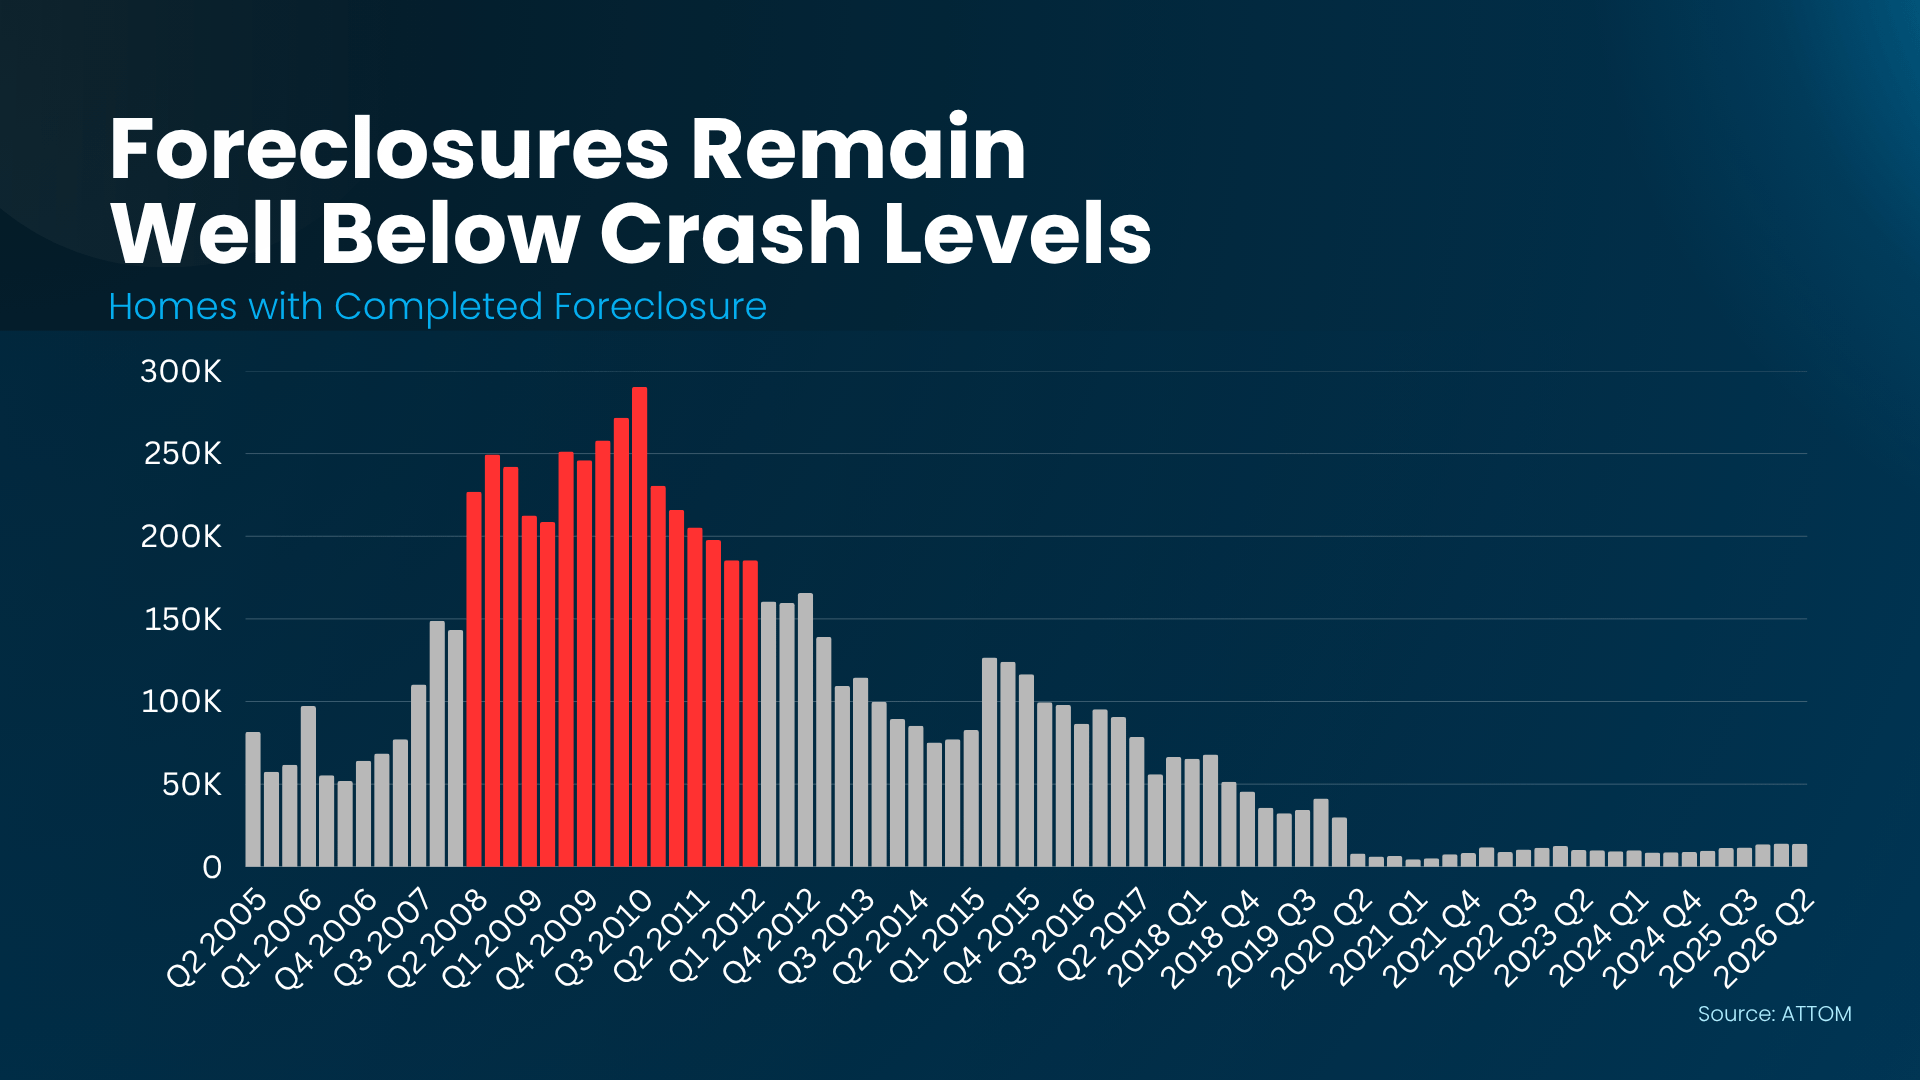
Completed foreclosures are up 33% from last year, according to ATTOM. That sounds like a big leap, but context helps.

Even with that increase, foreclosures are still about 26% below where they were in the first half of 2020.

Zoom out further, and today’s activity is a small fraction of what the market saw during the 2008 crash. Lenders completed about 28,000 foreclosures in the first half of 2026, according to ATTOM. Compare that to the crash years in red, when lenders often completed more than 200,000 in the span of a few months (see graph below):

a graph of a crash

Experts say today’s numbers reflect a housing market that’s still in good shape. As Rob Barber, CEO at ATTOM, explains:

“While some homeowners are still facing financial challenges, overall foreclosure volumes remain well below historical norms and the broader housing market continues to demonstrate resilience.”

And here’s why we can absorb the slight uptick in foreclosures we are seeing. 

Homes for Sale Are Back in a Balanced Range

During the crash, a lot of homeowners either lost their homes to foreclosure or were forced to sell, which left the market overwhelmed with houses for sale. That isn’t happening now.

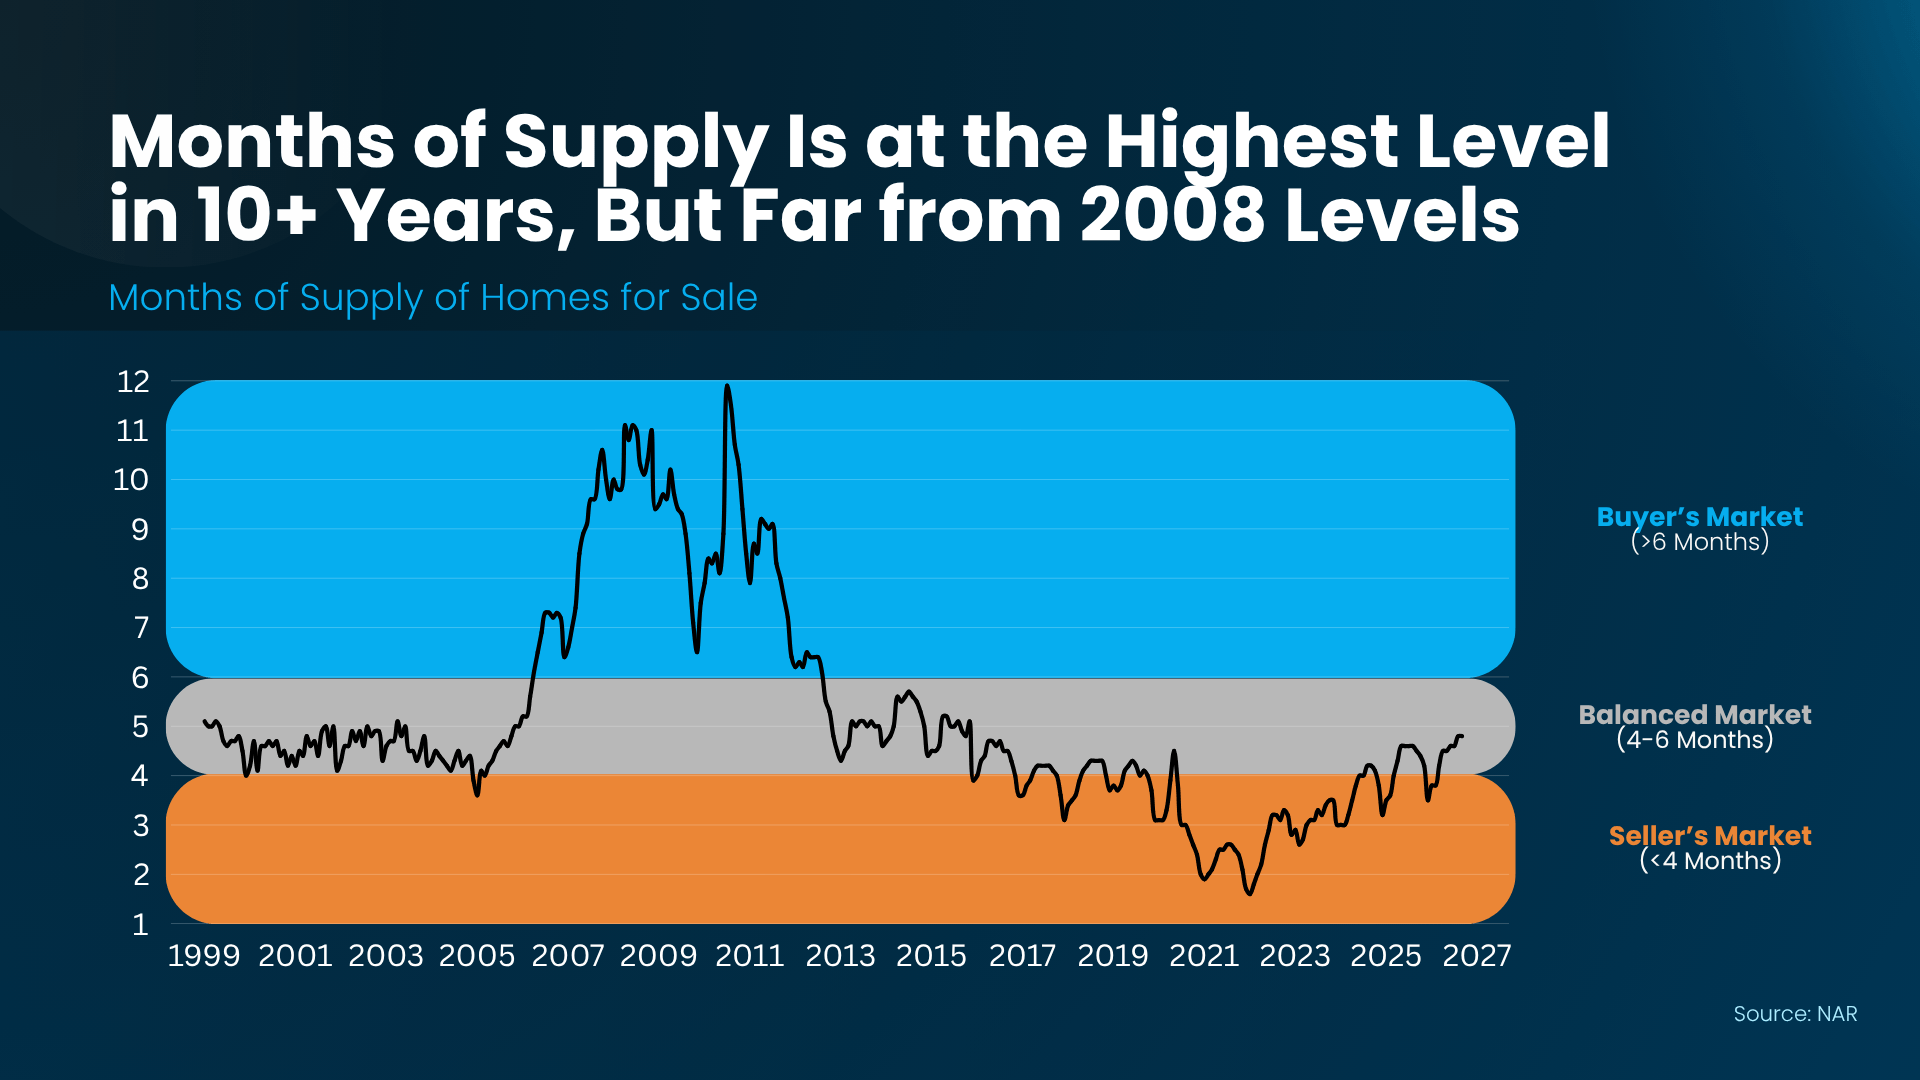
One way to see this is through months’ supply, which measures how long it would take to sell every home on the market at the current pace. Four to six months is considered balanced.

Right now, it’s about 4.8 months, according to the National Association of Realtors (NAR). That’s pretty well-balanced, and less than half of where it peaked around the last crash (see graph below):

a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

If foreclosures were really surging, you’d see it in the number of homes for sale. As Logan Mohtashami, Lead Analyst at HousingWire, explains:

“. . . a surge of actual foreclosures in 2026 would have easily put the inventory data much higher in 2026.”

Equity Gives Today’s Homeowners Options

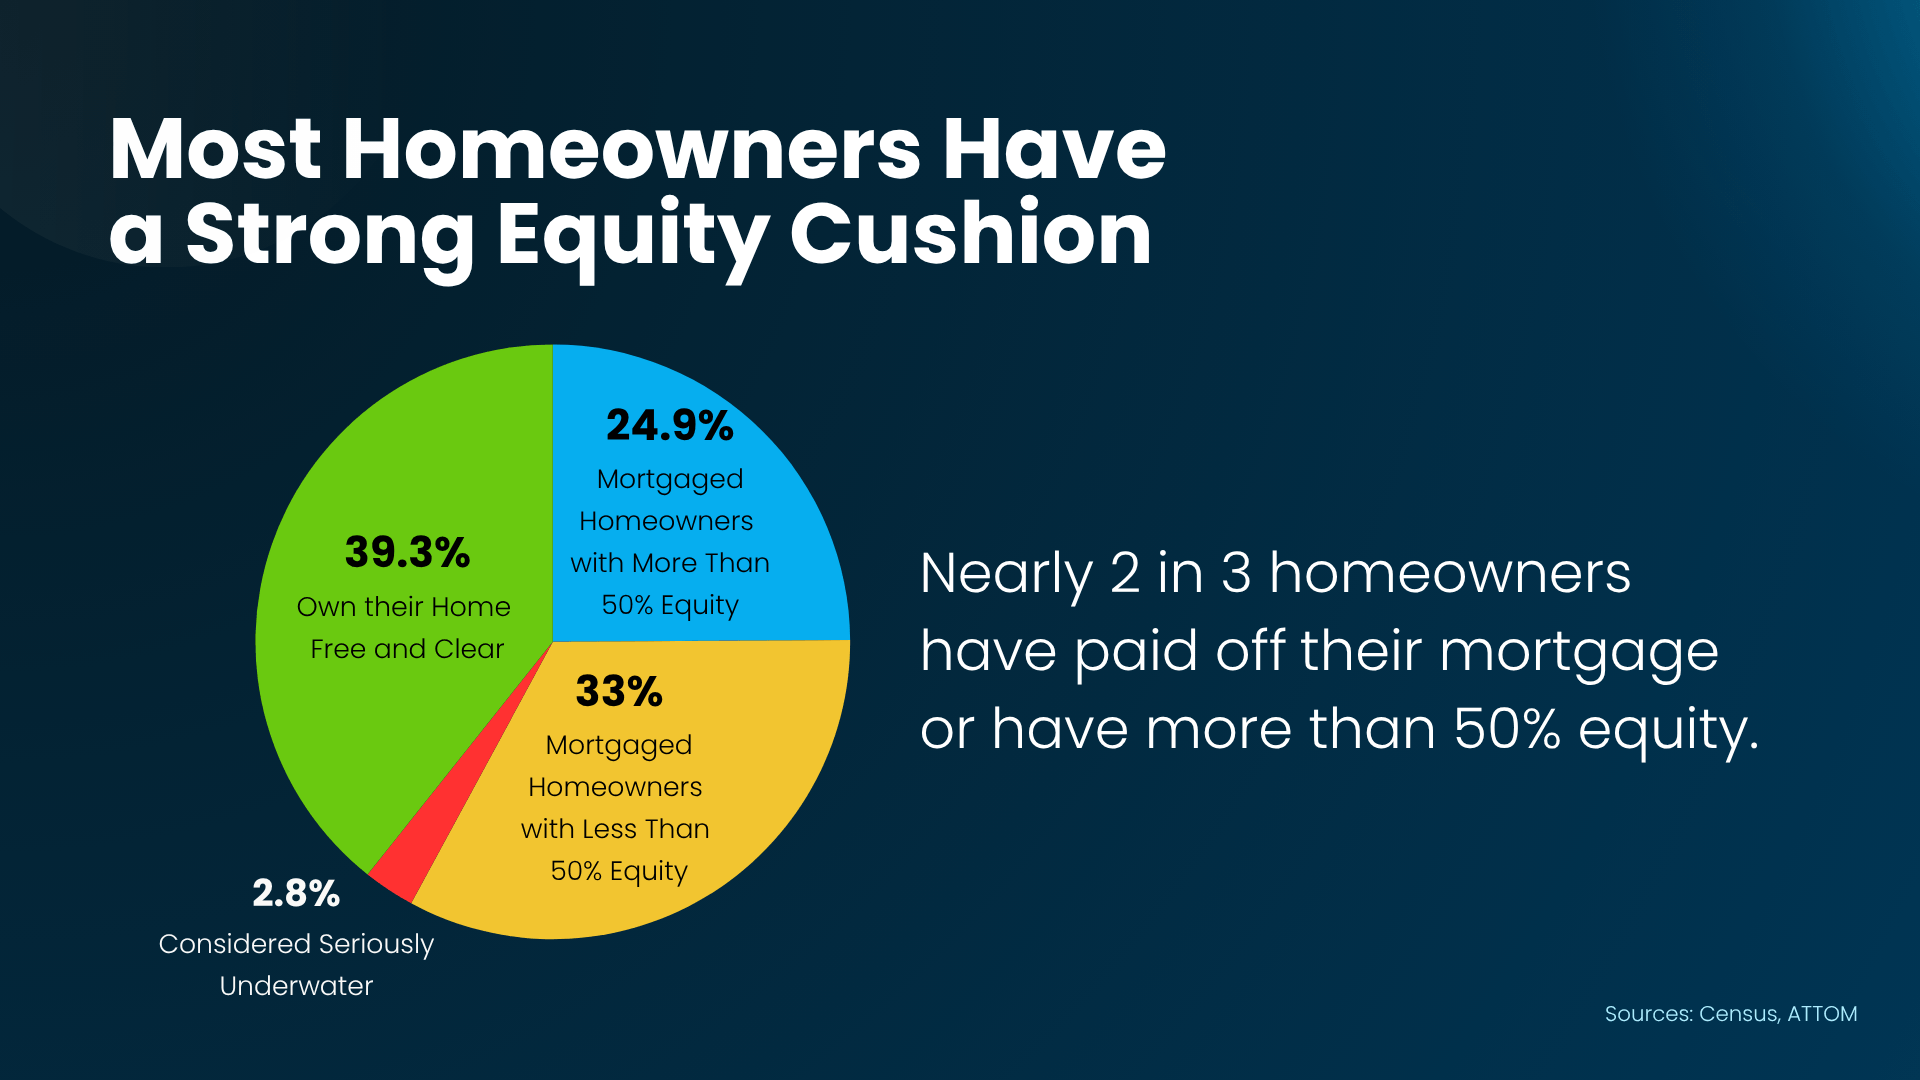
Equity is a big reason there’s no surge of distressed sales. Data from the Census Bureau and ATTOM shows nearly two in three homeowners have paid off their mortgage or have more than 50% equity. And Cotality says the average homeowner has about $310,000 in equity.

If a homeowner with equity hits a rough patch, they can usually sell their house, pay off the loan, and walk away with money in their pocket instead of facing foreclosure. That’s an option many people didn’t have during the crash. According to HousingWire, nearly one in four homes were underwater back in 2010.

Being underwater means owing more on your mortgage than your home is worth, which makes selling a lot harder. Today, just 2% of homeowners are considered seriously underwater (see graph below):

a pie chart with text on it
Not every homeowner has that kind of equity, but most do, and that’s what puts a ceiling on how high foreclosures can go.

Bottom Line

If rising foreclosures have you questioning where the housing market is headed, the data says it’s in good shape. The supply of homes for sale is balanced, and most homeowners have plenty of equity.

Have questions about what you’re seeing online, our local market, or about how much equity you have? Let’s talk.

Filed Under: Reverse Mortgages

admin November 11, 2026

Today’s Market Could Be a Win for Veterans Looking To Buy a Home

Today’s Market Could Be a Win for Veterans Looking To Buy a Home

November 11, 2026·3 min read

If you’re a veteran or active-duty service member who’s been hoping to buy a home, you may have more going for you in today’s housing market than you realize.

VA home loans already come with some pretty powerful benefits. But now, with more homes for sale and buyers having more room to negotiate in many markets, those benefits could go even further.

And if you’ve ever heard that buying with a VA loan is harder, takes longer, or puts you at a disadvantage, there’s something else you should know… a lot of what people believe about VA loans simply isn’t true.

The Benefits of VA Home Loans 

Today, nearly 4 million service members and veterans have an active VA home loan. And according to the Department of Veterans Affairs (VA), more than 343,000 homes were purchased using VA loan benefits in its most recent reported fiscal year. And it’s easy to see why.

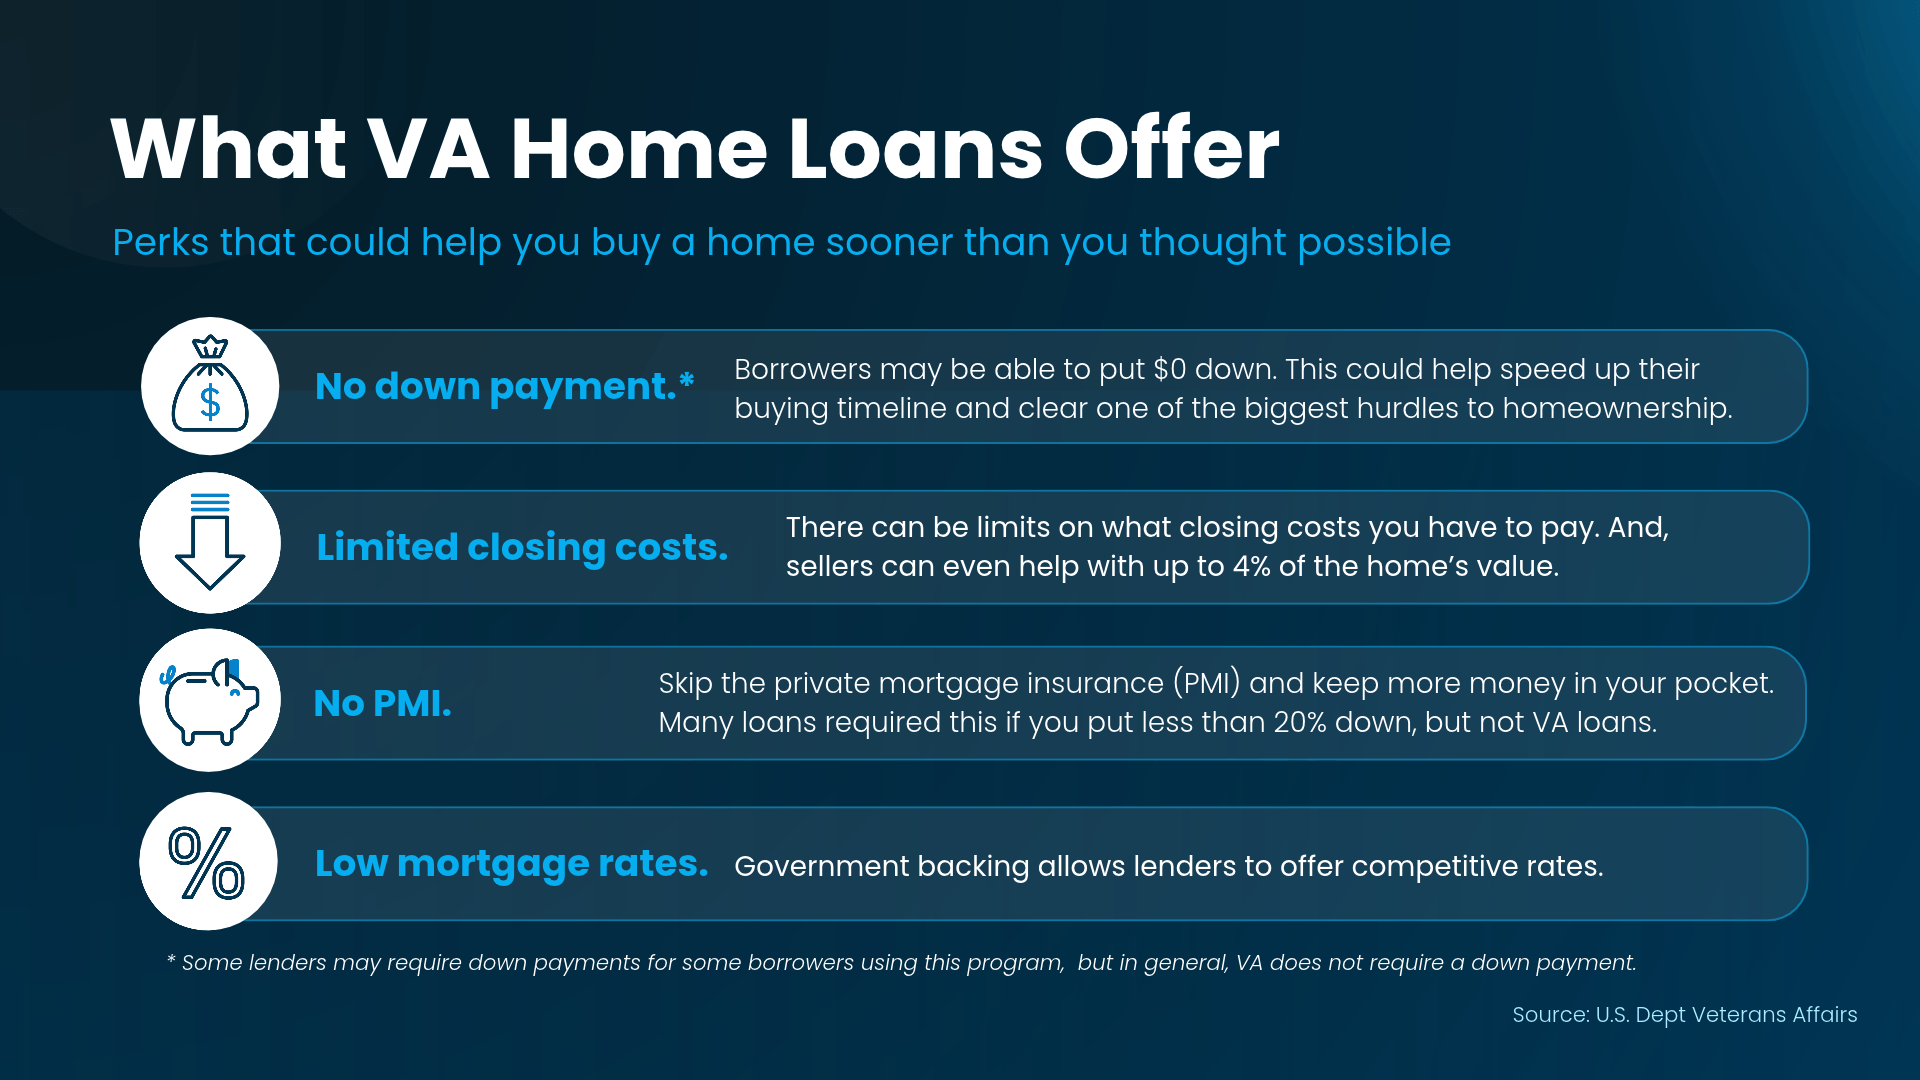
For eligible veterans and service members, VA loans offer advantages that can make buying a home more affordable, including:

  • No down payment required for many eligible borrowers.
  • No monthly mortgage insurance, even with no down payment.
  • Competitive mortgage rates that can help lower monthly payments.
a blue and white website with text

Benefits like this are powerful in any market – and even more so today. That may be why VA loan usage has grown for the last two years in a row.

Why Today’s Market Could Be Different for VA Buyers

A few years ago, when homes were getting multiple offers and buyers were competing for nearly every listing, VA buyers sometimes had a harder time getting their offers accepted.

A 2021 survey from the National Association of Realtors (NAR), found 89% of sellers were likely to accept an offer from a buyer using a conventional loan. But only 30% were likely to accept one using an FHA or VA loan.

The reason? Some sellers were concerned that VA financing would take longer, be more difficult to close, and require them to pay more in costs and repairs. But those concerns don’t necessarily reflect how VA loans actually perform.

VA Home Loan Myths vs. Reality 

A white paper from Vetted VA based on 2025 mortgage data busted a lot of VA loan myths:

Myth #1: VA loans get denied more often than other loans.

  • The Reality: VA loans actually have the lowest denial rate. Just 8.2% of VA purchase applications were denied, compared to 15.0% for conventional loans, 12.8% for FHA loans, and 12.5% for USDA loans. 

Myth #2: VA financing is less reliable.

  • The Reality: 90% of VA home loan applications that reached underwriting made it to closing, compared to 81% for conventional loans. 

Myth #3: VA appraisals take longer.

  • The Reality: VA loan appraisals typically take 7–10 business days, similar to conventional and FHA loans.

Myth #4: Sellers have to pay all the closing costs for VA buyers.

  • The Reality: VA buyers can pay many standard closing costs themselves. Buyers and sellers can also negotiate which eligible costs the seller will cover.

Today’s Market Gives VA Buyers More Leverage

Since there are more homes for sale and fewer buyers competing in many areas, sellers may be more open to different financing options than they were a few years ago. And the opportunity doesn’t stop at getting your offer accepted.

Depending on the house and your local market, you may also be able to negotiate a lower price, ask for repairs, or request help with closing costs.

VA guidelines allow sellers to cover the buyer’s normal closing costs, plus concessions of up to 4% of the home’s value.

Think about what that combination could mean. You may be able to buy with no down payment, avoid mortgage insurance, and negotiate help with some of the other expenses that come with buying a home.

That could mean keeping thousands of dollars in your savings instead of spending them upfront, giving you more breathing room after you get the keys.

Bottom Line

If you’re active duty, you’ve served, or you know someone who has, connect with a local agent and a trusted VA-approved lender to see what you qualify for.

Your VA home loan benefit and today’s market could be a powerful combination.

Filed Under: Reverse Mortgages

admin November 10, 2026

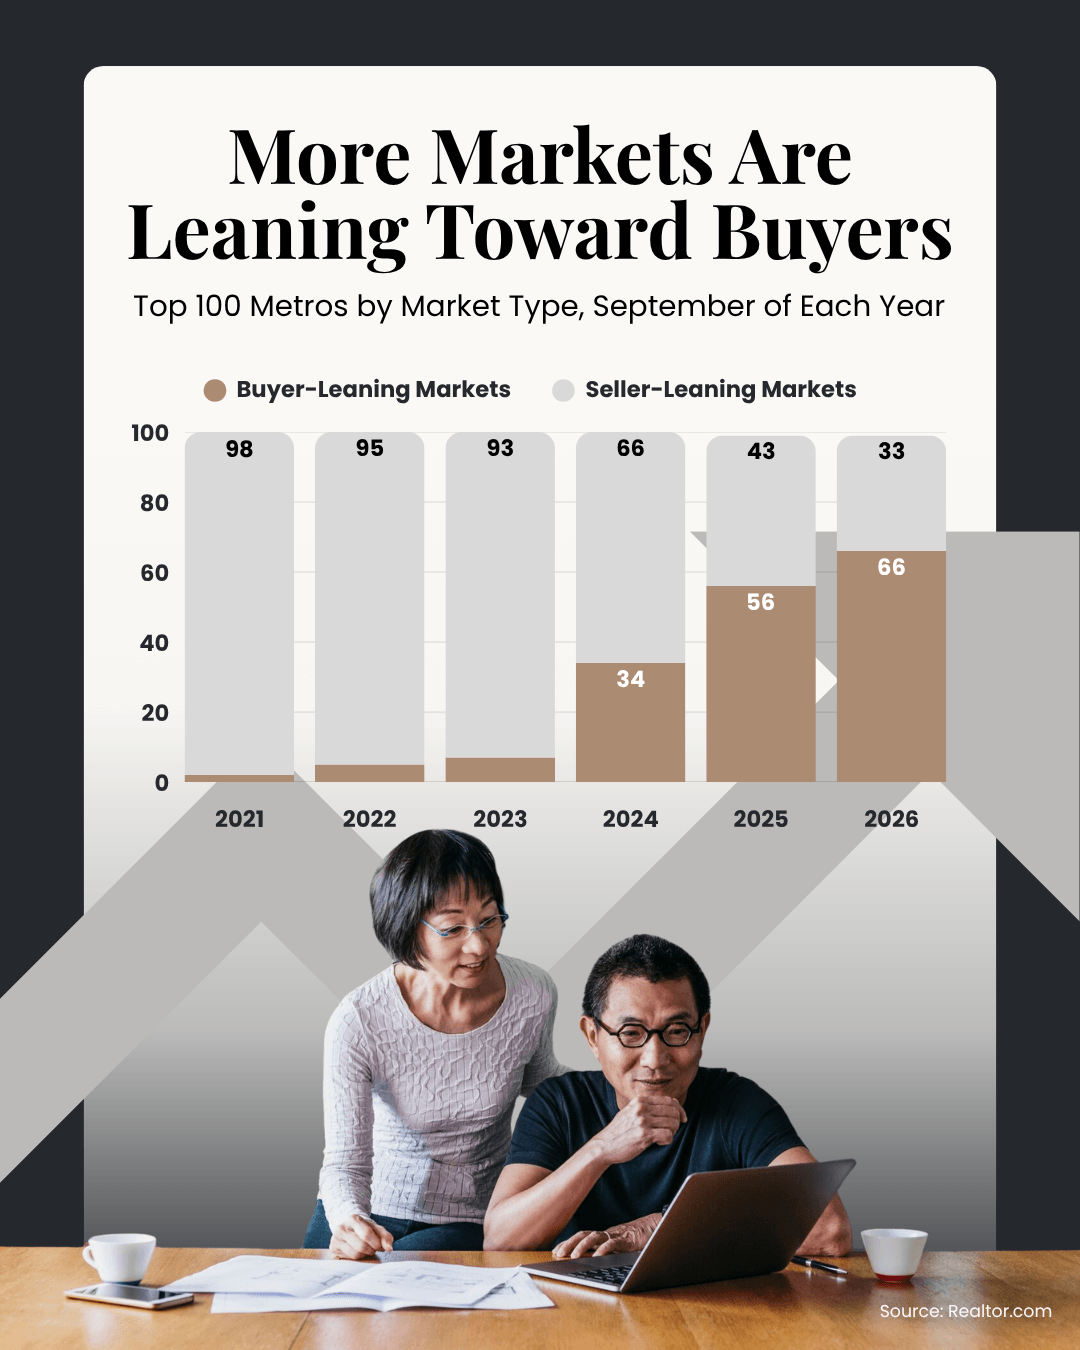
More Markets Are Leaning Toward Buyers Graph

Filed Under: Reverse Mortgages

admin November 9, 2026

Low Rates or Lots of Leverage? Buyers Rarely Get Both.

Low Rates or Lots of Leverage? Buyers Rarely Get Both.

November 9, 2026·3 min read

If you’ve been watching mortgage rates lately, you might feel a little stuck. Rates climbed above 7% this year, and a lot of buyers have decided to sit tight and wait for them to come back down.

But rates are only half the story. When you buy a home, you usually get one of two things: low rates or negotiating power. It’s rare to get both at the same time. And right now, you have a lot more of that second one than you might think.

Why Low Rates and Leverage Don’t Usually Show Up Together

Think back to 2020 and 2021. Rates were near 3%, and buyers rushed into the housing market. Those low rates sounded great, but they came with a catch. There were a lot of buyers just like you that you had to compete with – and there weren’t enough homes for sale to meet that demand. 

That’s why homes got multiple offers, buyers paid over asking or waived inspections, and sellers held all the cards. Jake Krimmel, Senior Economist at Realtor.com, shows just how one-sided things got:

“Seller’s markets peaked at 98 of 100 metros in spring 2022 after two years of mortgage rates near 3%.”

Then, in the second half of 2022, rates went up. As a result, the number of people buying homes went down, inventory grew, and the balance slowly started tipping from sellers back to buyers. Fast forward to today, and that flip is officially here. 

In a recent report, Realtor.com found about two-thirds (66) of the top 100 metros now lean in favor of buyers (see graph below):

a blue and orange pie chart

And while you may want lower rates, this shift in power has its own perks.

What Your Leverage Looks Like Right Now

There are more homes for sale than there have been in years. And in a more buyer-friendly market like that, it means sellers have to work harder to get their homes sold. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:

“Higher inventory and lengthening days on market give buyers improved negotiating power.”

That shows up in the deals buyers are getting. According to Redfin, nearly half of buyers now get some kind of concession from the seller – like help with closing costs, money for repairs, or even the seller paying to buy down your mortgage rate (see graph below):

a graph of sales growth

So when you find a home you love, even if the rate isn’t what you necessarily wanted, there are other levers to pull. Ask about a price cut or a seller-paid rate buydown, too. It could take some of the sting out of today’s rates.

Why Waiting for Lower Rates Could Backfire

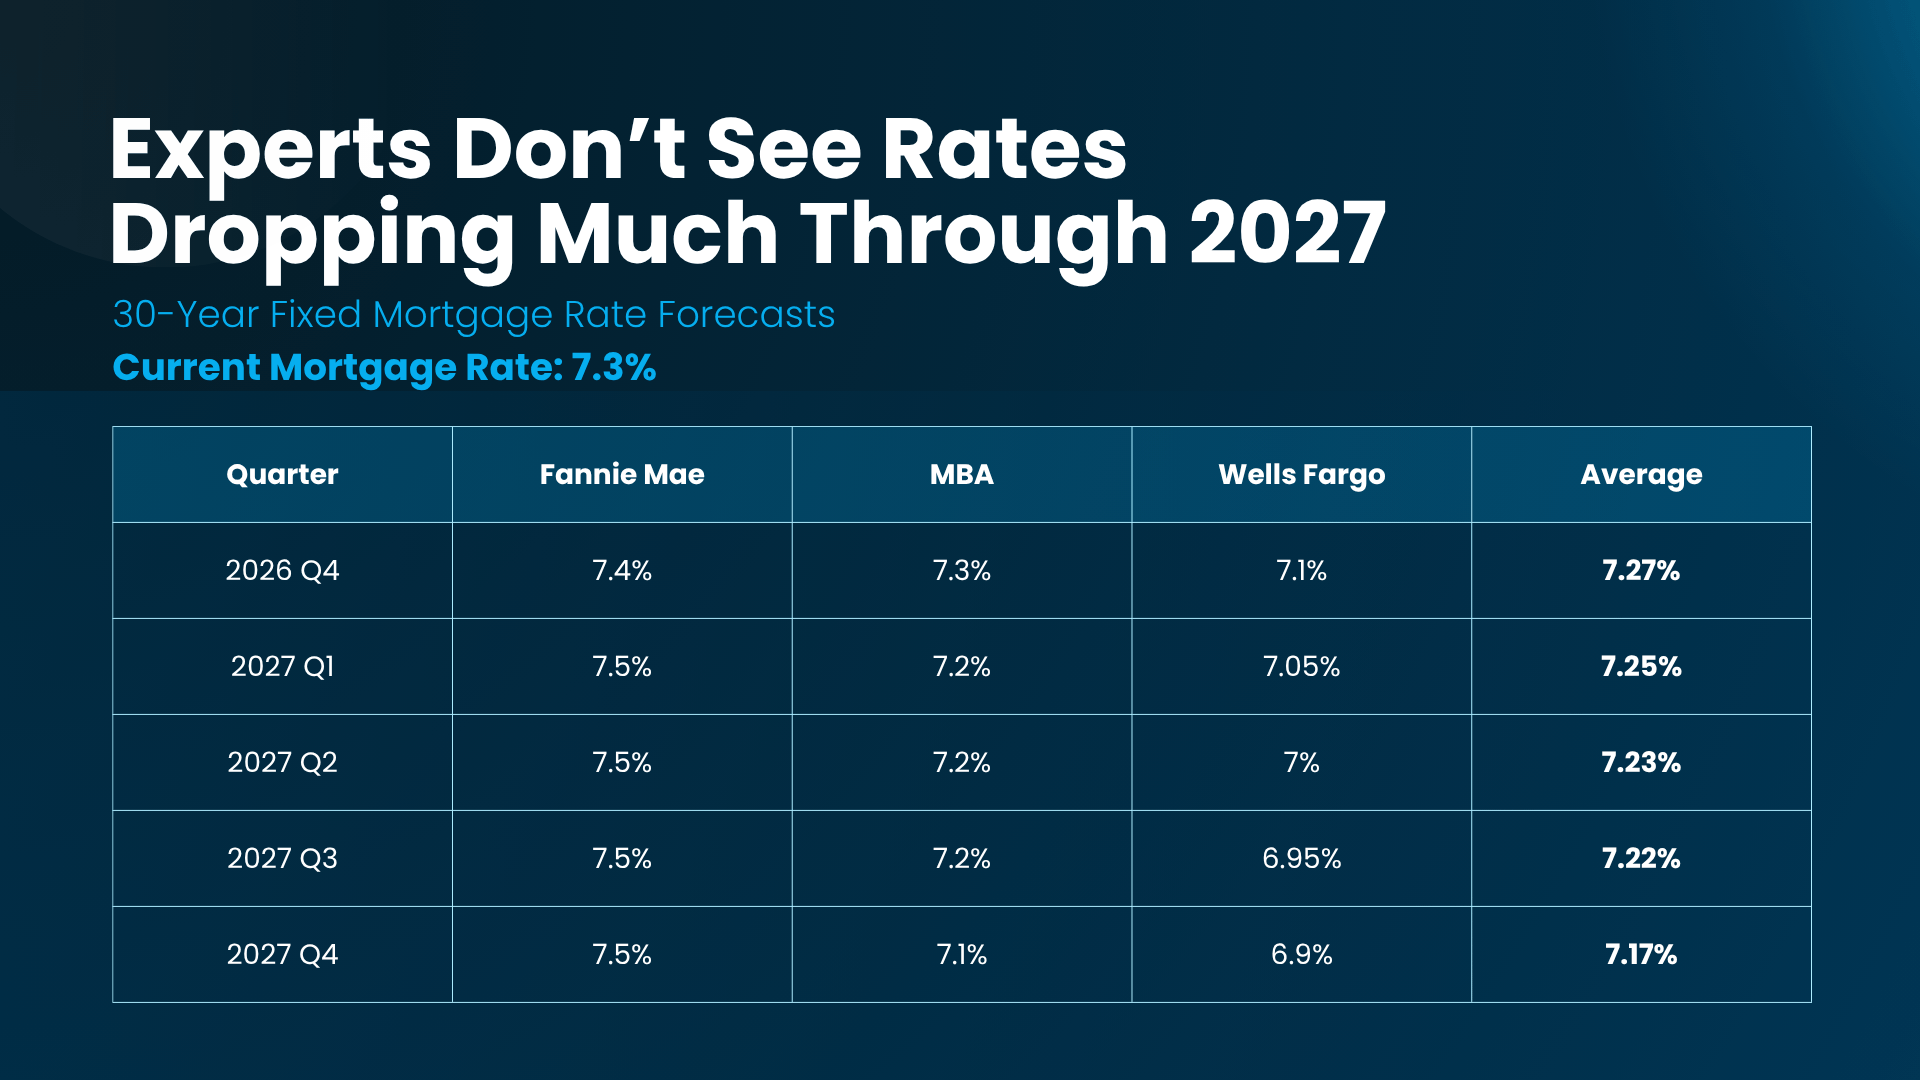
And just in case you’re still thinking you’ll just hold off until rates drop, here’s what you should know. Experts at Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo don’t expect rates to fall much through 2027 (see graph below):

a blue and white graph with white text

And here’s the whole point. Even if rates did drop in a big way, a lot of buyers would rush back in. More competition means fewer deals, fewer concessions, and sellers getting the upper hand again.

So waiting comes with a trade-off. You might land a better rate down the road, but you’d probably give up the bargaining power you have today.

That doesn’t mean you have to move right now. You should only buy when the numbers work for you. But if you’ve got a real reason to move, today’s leverage could help make your numbers work – even at today’s rates.

Bottom Line

Buyers rarely get low rates and strong negotiating power at the same time, and today’s market is handing you the leverage. 

Let’s find homes where sellers may be open to covering a rate buydown or closing costs, so you can see if today’s market can work for your budget.

Filed Under: Reverse Mortgages

Next Page »

Get More Information About East Coast Capital

Fill out the form below to learn more about Reverse Mortgages offered by East Coast Capital.

  • I agree to be contacted by Robert D. Gersh, via call, email, and text for mortgage services. To opt out, you can reply "stop" at any time or reply "help" for assistance. You can also click the unsubscribe link in the emails. Message and data rates may apply. Message frequency may vary. https://askbobgersh.com/privacy-policy/

Explore Our Site:

  • Questions
  • Are You Eligible for a Reverse Mortgage?
  • What About Counseling?
  • Moving Soon?
  • Have Use for the Money?
  • Want to stay in your own home?
  • Is a Reverse Mortgage Right for You?
  • One Time Large Expense?
  • What kind of home do you own?

Serving The Villages, Florida

Follow Us!

  • Facebook
  • LinkedIn
  • Twitter
  • YouTube

Our Newsroom:

  • A Mortgage Rate Buydown Could Make Your Next Home More Affordable
  • 3 Things Sellers Need To Know About Pricing Today
  • 3 Housing Questions That Might Come Up at Your Next Family Dinner
  • Homeowner Net Worth Has Nearly Doubled Since 2010
  • A Fixer-Upper Could Be Your Path To Homeownership

© 2026 · Bob Gersh, Reverse Mortgage Coordinator, East Coast Capital, 670 State Road 1st Floor, North Dartmouth, MA 02747 | Privacy Policy