3 Housing Questions That Might Come Up at Your Next Family Dinner
November 18, 2026·3 min read
This time of year usually means more time spent with family and friends. And in recent years, when everyone gets together, the conversation has a way of drifting to housing.
Your uncle is sure home prices are about to crash. Your cousin heard foreclosures are surging. And someone across the table brings up the word “recession.”
If you’ve wondered about any of this yourself, that makes sense. There’s a lot of noise out there. So let’s look at what the data actually shows, so you’ll have real answers the next time it comes up.
“Are Home Prices Going To Crash?”
Let’s start with your uncle’s crash prediction. The short answer is no. Experts project home prices will keep climbing nationally in 2027.
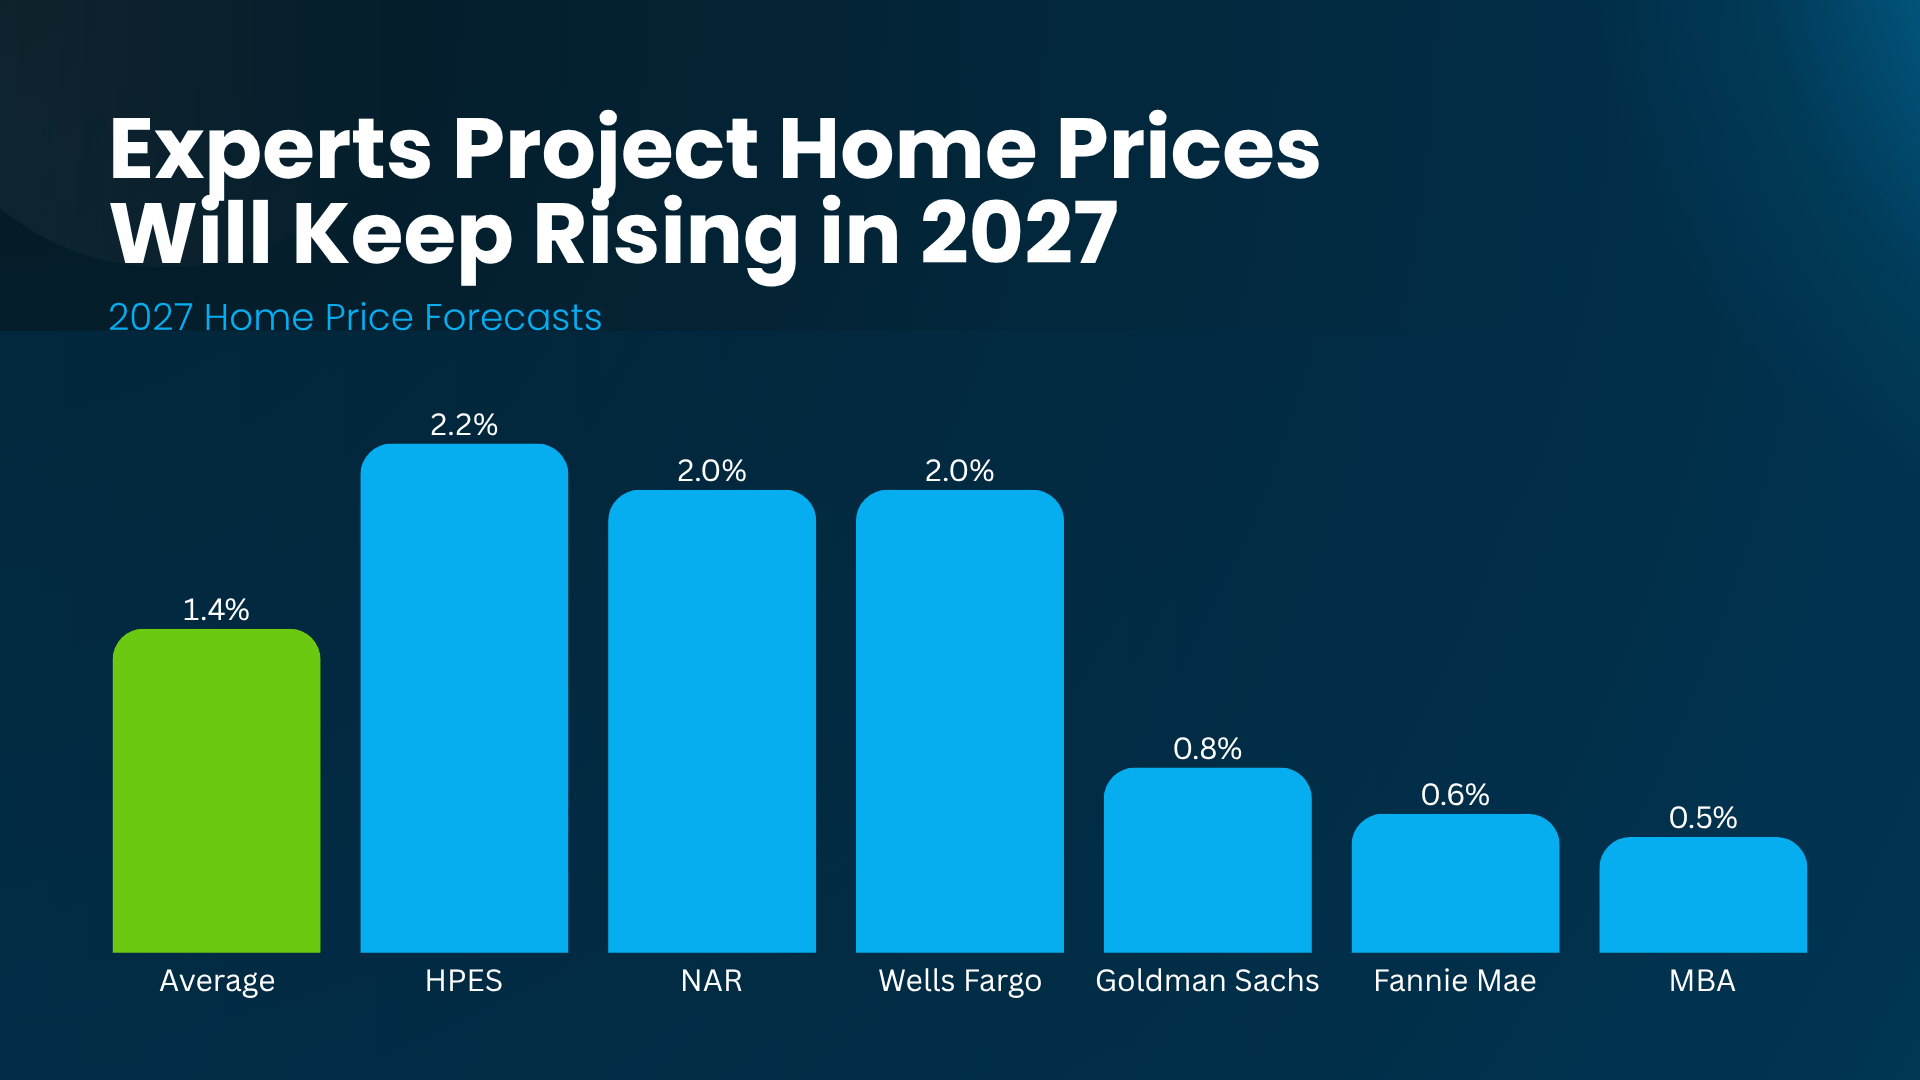
On average, forecasters expect prices to rise about 1.4% next year (see graph below). That’s slower than the big jumps of a few years ago, but it’s still growth, not a crash.
Prices are dipping in some markets, though. It just depends on where you live. Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains why:
“Price declines are occurring mainly in southern states, where there has been robust new home construction in recent years. Given the region’s faster job growth, these price drops should be viewed as temporary and as a second-chance opportunity for those previously priced out of the market.”
So, the dips that are fueling all the social media chatter are limited to select areas, and experts think they’ll be short-lived. It doesn’t mean a crash is looming.
If you’re thinking about moving, look at the numbers for your area.
“Is This 2008 All Over Again?”
Then your cousin chimes in about foreclosures. They’ve ticked up lately, but here’s some important context. That’s compared to very low levels. They’re still below where they were before the pandemic, according to ATTOM.
So, why doesn’t today look like 2008? Logan Mohtashami, Lead Analyst at HousingWire, explains:
“. . . we have had many recessions post-WWII but only one foreclosure crisis. That foreclosure crisis started with a massive credit boom from 2002-2005, and then a credit bust. . . none of that is happening now . . .“
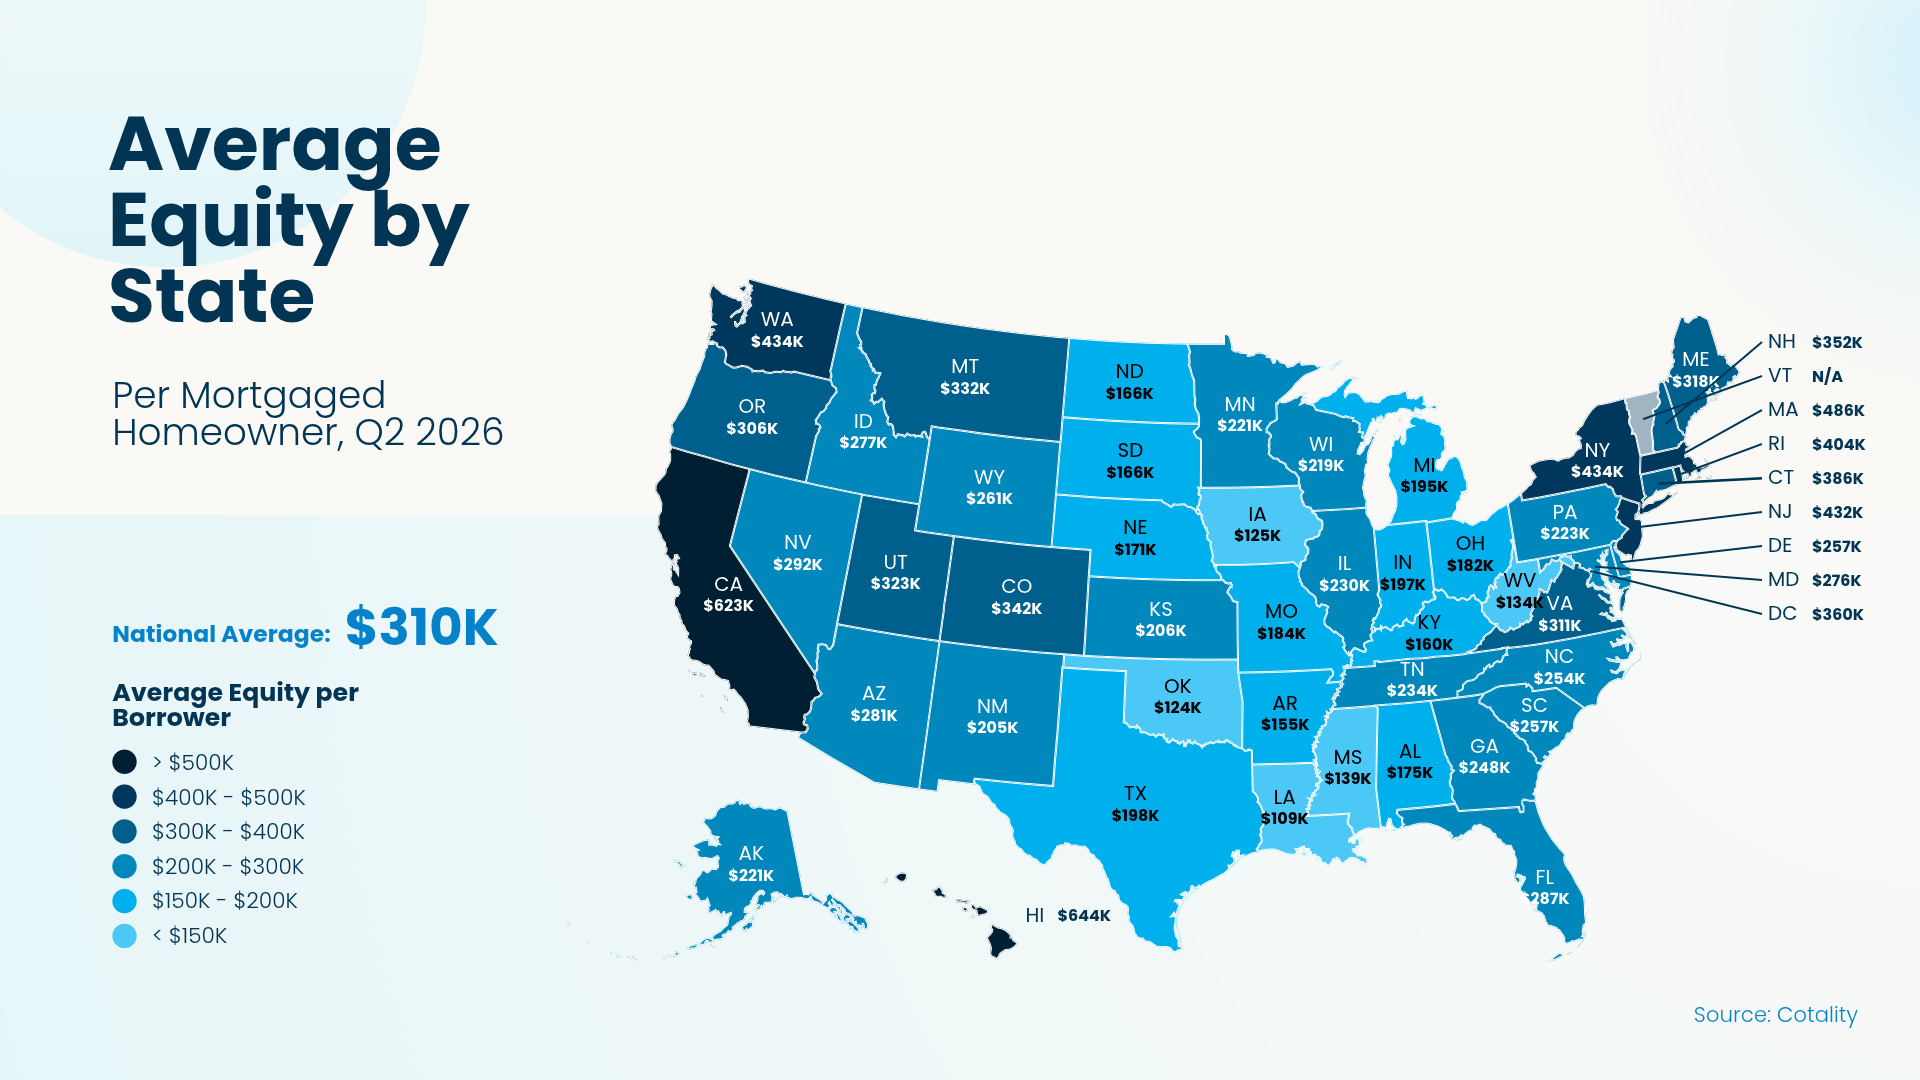
Today’s homeowners also have something a lot of people didn’t have back then – equity. In every state, the average homeowner with a mortgage has more than $100,000 of it, according to Cotality (see map below):
If a homeowner hits a rough patch, they can usually sell their house instead of facing foreclosure.
“Are We Headed for a Recession?”
While someone in your family may be convinced a recession is coming, experts don’t agree. The average forecast from The Wall Street Journal’s survey of economists puts the odds at about 24%, so most experts aren’t expecting one. And that’s a good thing.
But even if one hits, history shows a recession doesn’t mean home prices will automatically fall. In 5 of the last 6 recessions, prices actually went up, according to the Federal Housing Finance Agency (FHFA) (see graph below):
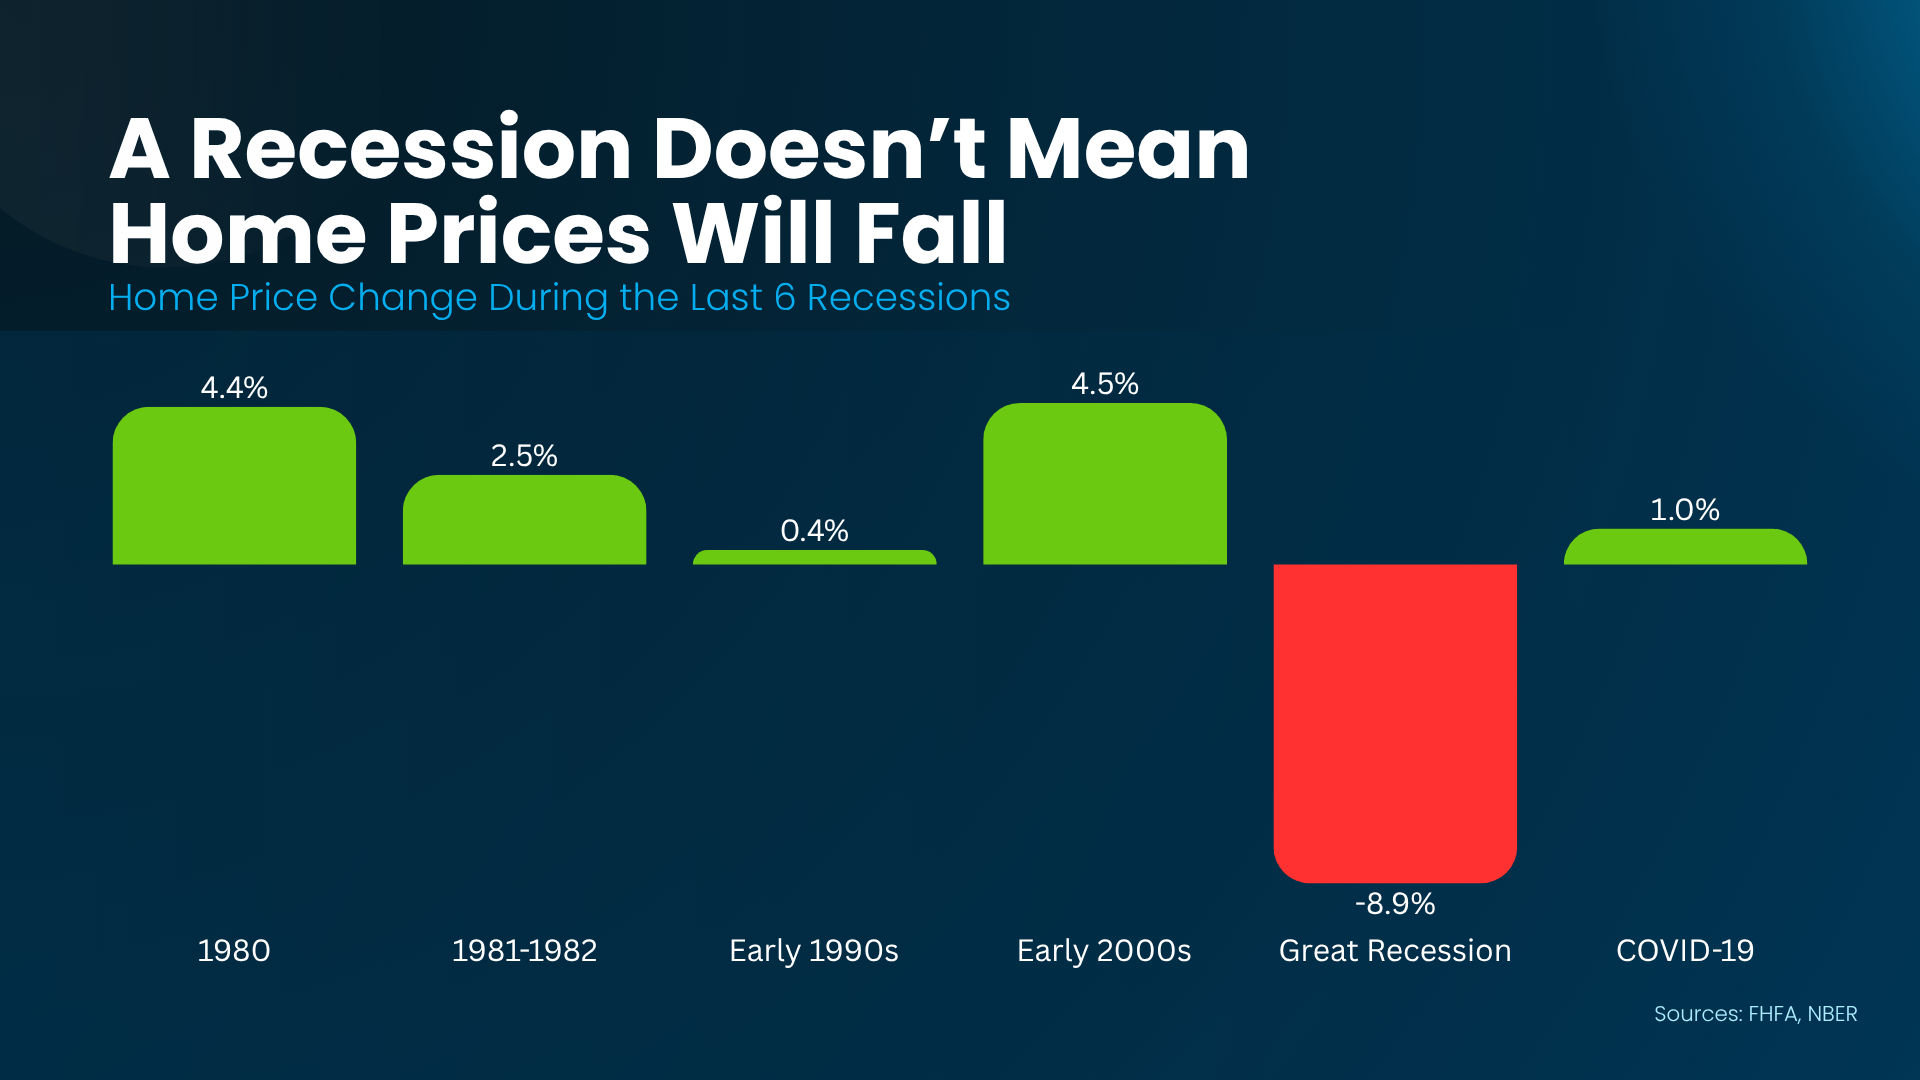
The one exception was 2008, the only one of these recessions that started in the housing market itself.
Bottom Line
So, the next time your uncle predicts a crash or your cousin brings up 2008, you’ll know prices aren’t crashing, foreclosures are still low, and a recession doesn’t automatically spell trouble for housing.
If a move in 2027 is on your mind, let’s look at what prices are doing in your neighborhood so you can plan with real local numbers, not scary headlines.