Mortgages, Refinance and Reverse Mortgages in The Villages, Florida

Helping Village Residents stay in their homes.

Simplifying Reverse Mortgage in The Villages, Florida

Speak to Bob Gersh now by calling: 352-561-3096 or
1-866-576-5254 ext. 700

Click Here To Set Up a Free Consultation.

  • Home
  • Myths
  • Questions
    • Are You Eligible?
    • Counseling
    • Moving Soon?
    • Use for the Money?
    • Live in your Own Home Forever.
    • Is a Reverse Mortgage right for you?
    • One time large expenses.
    • What kind of home do you own?
  • Reverse Mortgage Basics
    • The Villages, FL
  • Blog
  • About
  • Podcast
  • Local Resources
  • Platinum Years
  • Contact
  • Realtor Tools

Is a Reverse Mortgage Right for You? Learn More…

As more and more mortgage companies are "jumping on the bandwagon" offering reverse mortgages, here are two facts you should know:

  • Most companies who offer reverse mortgages simply broker or sell your loan to one or two of the large wholesalers.
  • Most companies offer similar products and programs.

What does that mean for you?

You should be looking for a reputable company who you can trust to give you professional advice on whether or not you are a good candidate for a reverse mortgage…not just whether or not you qualify. A reverse mortgage is an excellent program, but it's not right for everyone.

  • Senior Couple Meeting With Financial Advisor At Home
  • Senior man doing calculation at home
    Senior man busy doing calculation, counting money and bills at home, sitting at desk.
  • Miniature house over money isolated
    Miniature house over money isolated on white background
We will provide you with a free, no-obligation personalized Suitability Report that will help you determine not only if you qualify for a reverse mortgage...but if a reverse mortgage is a good option for you.

East Coast Capital is an organization of honest, ethical, knowledgeable professionals who will give you the straight answers. Reverse Mortgages are our business.

Call Bob Gersh Today 352-561-3096 or 1-866-576-5254 ext. 700

Company NMLS# 1810279

MLO Timothy Bradford NMLS 21031

Mortgage Lender License# MLDB8675 - dba Coast to Coast Capital Corp - Florida Office of Financial Regulation
Reverse Mortgage  The Villages FLReverse Mortgage  The Villages FLReverse Mortgage The Villages FLReverse Mortgage  The Villages FL

Get More Information About Reverse Mortgages

Fill out the form below to learn more about Reverse Mortgages offered by East Coast Capital.

  • I agree to be contacted by Robert D. Gersh, via call, email, and text for mortgage services. To opt out, you can reply "stop" at any time or reply "help" for assistance. You can also click the unsubscribe link in the emails. Message and data rates may apply. Message frequency may vary. https://askbobgersh.com/privacy-policy/

admin December 1, 2025

How To Find the Best Deal Possible on a Home Right Now

How To Find the Best Deal Possible on a Home Right Now

BLOGDecember 1, 2025

For BuyersFirst-Time BuyersBuying Tips


2 min read

Want to know how to find the best deal possible in today’s housing market? Here’s the secret. Focus on homes that have been sitting on the market for a while.

Because when a listing lingers, sellers tend to get more realistic – and, more willing to negotiate. And that’s where the savviest buyers are finding homes other buyers overlook.

The Opportunity: 1 in 5 Homes Has Had a Price Cut This Year

According to Realtor.com, about 1 in every 5 listings (20.2%) have dropped their asking price at least once. And while so many things in today’s housing market vary by region, that number is consistent throughout the country. That tells you one thing…

No matter where you live, there’s a chance to score a better deal. You just need to know where to look. And that’s where your agent comes in.

The Tactic: Target Homes That Have Been Sitting the Longest

Your agent can help you identify which homes have been on the market the longest. Those are the ones where you’re more likely to get a discount. That’s because the seller may be getting frustrated their house hasn’t sold yet, so they’re more willing to play ball.

And since a lot of buyers steer clear of homes that aren’t selling, you may be the only offer they get. So, you can lean in and push for a better deal. As Realtor.com explains:

“Less competition means fewer bidding wars and more power to negotiate the extras that add up: closing cost credits, home warranties, even repair concessions . . . these concessions can end up knocking thousands of dollars off the price of a home.”

And they’re not the only ones calling out the opportunity you have right now. Bankrate also says:

“During the quieter fall and winter months, when fewer prospective buyers are shopping, home sellers may be more willing to lower their prices, or offer concessions, to attract those prospective buyers who are still looking.”

And the proof is in the data. The National Association of Realtors (NAR) shows a clear pattern: the longer a home stays on the market, the lower it tends to sell for compared to the original asking price.

So, if you’re serious about getting as much as you can for your money, focusing on these listings could be your best strategy yet.

Even a Small Discount Can Go a Long Way

And while paying 94% of the original asking price may not sound like much of a deal, the savings add up. That’s roughly $24,000 in savings on the median priced home (see chart below):

Zillow sums it up best:

“If you’re a buyer who is hoping to strike a deal, look for homes that have been on the market for a while and that may already have lowered prices to entice buyers. You may find a motivated seller who is more willing to negotiate.”

Bottom Line

If you want to find the best deal possible on a home right now, start by looking where others aren’t.

With 1 in 5 sellers cutting prices and many growing more flexible by the week, the homes that have been sitting a little longer could be your best opportunity to save.

Let’s talk about where to find them in our area.
Filed Under: Reverse Mortgages

admin November 27, 2025

Why So Many People Are Thankful They Bought a Home This Year

Why So Many People Are Thankful They Bought a Home This Year

BLOGNovember 27, 2025

For BuyersFirst-Time BuyersMove-UpDownsize


2 min read


Homebuyers are weighing their options right now, and they certainly have a lot on their minds. With everything going on in the job market, the economy, and more – there’s a lot to think about these days. And maybe that’s making you wonder if it really makes sense to buy a home right now.

But here’s what many recent buyers would tell you: even with all that, making a move is worth it.

And this is why they’re thankful they went ahead and took the plunge already. Life doesn’t wait for better market conditions. So, your decision shouldn’t be about trying to time the market perfectly. It should be about moving when the time is right for you and what you need – and it’s different for everyone.

The Real Reasons People Bought a Home

According to the latest report from the National Association of Realtors (NAR), what’s really driving today’s moves is the desire for something better or something different. It’s a personal motivator or a change in what they need out of the home that pushed buyers to act this year (see chart below):

For some, that meant trading an apartment for their very first house – a home they can finally make their own, where they can paint the walls, plant the garden, and build a future.

For others, it meant getting closer to the people who matter most. Living near family or friends isn’t just convenient, it changes your everyday life. Sunday dinners, quick visits, extra help when you need it – that kind of connection is priceless.

And for many buyers, it’s the peace of finding a home that finally fits. It’s finally having space to grow: a bigger kitchen for family dinners, or bedrooms where kids can decorate their own walls and carve out their own corners of the world.

Or, it’s about simplifying. Downsizing to something smaller, easier to maintain, and closer to what matters most can make everyday life feel lighter and less stressful.

What You Miss Out on If You Try To Time the Market

No matter the reason, these buyers all share something in common: they stopped waiting for perfect timing and focused on creating the life they wanted now. And if you asked them, odds are they’d say that decision is paying off every day.

That’s what makes a move meaningful. Not the market conditions, but the freedom and happiness that come from living in a home that truly fits. So, while headlines may keep everyone guessing, the people who’ve already made their move are sleeping better, living fuller, and enjoying homes that finally feel right.

Because once your home finally matches your life, everything else starts to fall into place. And that’s exactly how you deserve to feel. 

Bottom Line

The people who bought a home this year didn’t wait for perfect market conditions to line up. They acted on what they needed in their life. And they’re thankful they did.

If you’re feeling the pull toward something better, let’s talk through your goals. Your next home could bring you more space, more connection, and more happiness than you think.

Filed Under: Reverse Mortgages

admin November 26, 2025

Why Buying a Home Still Pays Off in the Long Run

Why Buying a Home Still Pays Off in the Long Run

BLOGNovember 26, 2025

For BuyersFirst-Time BuyersRent vs. BuyAffordability


3 min read


Renting can feel much less expensive and much simpler than buying a home, especially right now. No repairs, no property taxes, no worrying about mortgage rates – you just pay the bill and move on with your life.

But here’s the part people don’t talk about enough: renting doesn’t help you build your financial future. Meanwhile, homeowners grow their net worth just by owning a home.

So, if you’ve been wondering whether buying is still worth it, the long-term math is clearer than you might think.

Renting vs. Owning: How the Costs Really Compare

Let’s break down one of the key differences between renting and buying. When you rent, your payment goes to your landlord, and then it’s gone. When you own, part of your payment comes back to you in the form of equity (the wealth you build as the value of your home increases, and you pay down your home loan).

So, while renting may seem more affordable now, you have to remember it comes at a long-term cost: you’re not building your wealth. And it turns out, that’s a bigger miss than you may expect.

First American recently analyzed the long-term financial impact of renting versus owning a home. They compared mortgage payments, property tax, insurance, repairs, and maintenance against the equity gained through home price appreciation and paying down the mortgage. And they did that during several different time frames to see if it tells a consistent story:

  • 2006: the start of the housing bubble
  • 2015: 10 years ago
  • 2019: just before the pandemic (the last normal years in the market)
  • 2022: when mortgage rates jumped

In each time frame, two things were true: renters ended up losing money over time. And homeowners gained it.

Here’s some data so you can see this play out. Each color represents one of the key time frames. The solid lines show the buyer’s investment over time and how their net worth actually grew the longer they lived in their home. The dashed line represents the renter’s investment. In the end, they sank more and more cash into renting without gaining any financial benefit.

The takeaway is simple: time in a home builds wealth. Time renting doesn’t.

Basically, homeowners come out ahead. And the analysis shows that’s even after you factor in the other expenses that come with homeownership, like insurance, repairs, and property taxes. And that’s the case for every time frame First American looked into.

On the flip side, renters spent money on their rent, but didn’t gain any long-term financial benefit. That’s true no matter what window of time you look at in the study.

Now, that doesn’t mean buying always beats renting in the short term. But the longer you own, the wider the wealth gap becomes.

Affordability Is Starting To Improve

You might still be thinking, “Okay, but buying feels out of reach for me right now.” Fair.

The past few years haven’t been easy for buyers. But things are starting to shift. Mortgage rates have come down this year, home prices are softening, and incomes have been rising. And according to Zillow, typical monthly payments have gotten a little easier compared to this time last year. Not by a lot, but enough to make a difference.

No, buying isn’t suddenly easy. But it is easier than it was just a few months ago. And in the long run, history shows it’s worth it. 

Bottom Line

Renting may feel less expensive today, but owning is what builds real wealth over time. And with affordability starting to improve, the path to homeownership may be opening up more than you think.

If you’re curious what buying could look like for you, let’s connect. We can figure out your next move, pressure-free.

Filed Under: Reverse Mortgages

admin November 25, 2025

Thank You for your business and referrals this year

Filed Under: Reverse Mortgages

admin November 24, 2025

4 Reasons Your House Is High on Every Buyer’s Wish List This Season

4 Reasons Your House Is High on Every Buyer’s Wish List This Season

BLOGNovember 24, 2025

For SellersInventorySelling Tips


3 min read


When the holidays roll around, travel plans, family gatherings, and all the chaos of the season may make you think it’s better to pull your listing off the market or to wait until 2026 to sell your house. But here’s the thing.

Waiting could mean missing out on a great window of opportunity. Because while other sellers are stepping away, you can lean in – and that might actually give you the edge. Here are 4 reasons selling now may be the better bet. 

1. Buyers This Time of Year Are Serious

Don’t let the season fool you. While casual browsers tend to step back around the holidays, serious buyers stay in the game. The people looking for homes right now usually aren’t just browsing. They’re ready to make a move and they usually want to close before the new year. As Zillow says:

“While more buyers have tended to shop in the spring and summer months, those shopping in the winter are likely to be motivated — often moving because of a job relocation, change in financial situation, or change in family needs.”

Their timelines are real and missing them would create a hassle for the buyer, so they’re eager to get the deal done. And that’s exactly the kind of buyer you want to work with.

2. You Have Control Over Your Schedule (and Showings)

Some homeowners decide not to sell this time of year because they don’t want to juggle showings during the holiday rush. They’re anticipating traveling to see family and thinking about buyers in their home only adds another layer of complexity. 

But here’s what no one’s reminded them. You can control your showings and can set times that work for your schedule. You don’t have to stop your plans to keep your sale on track. The right agent can help you manage your calendar, your showings, and your stress level.

3. Other Sellers May Step Back, Which Means Less Competition

Because fewer sellers tend to list this time of year, the number of homes for sale usually falls a bit. Lisa Sturtevant, Chief Economist at Bright MLS, explains:

“As we approach the end of the year, listing activity tends to slow and would-be sellers decide to wait until after the new year to list . . .”

And in a year when inventory has been steadily rising, that seasonal slowdown works in your favor. With the potential for fewer sellers on the market, your house will stand out. So, a seasonal dip in listings could help you get noticed, especially if your home is priced right and presented well.

4. Homes Decorated for the Holidays Can Feel More Inviting

You may not realize it, but seasonal decor can actually help you appeal to buyers. Maybe it’s that they have an easier time picturing themselves making memories in the home. Maybe it just feels cozier and more inviting. Whatever the reason, it works. Sometimes tasteful seasonal touches can make it easier to sell your house.

But don’t go overboard. Keep your choices simple to let your home’s charm shine through.

Bottom Line

There are plenty of good reasons to put (or keep) your house on the market during this time of year.

If you want to talk strategy for how to make the most of this season in our market, let’s connect.

Filed Under: Reverse Mortgages

admin November 20, 2025

Most Experts Are Not Worried About a Recession

Most Experts Are Not Worried About a Recession

BLOGNovember 20, 2025

For BuyersFirst-Time BuyersBuying TipsEconomy


3 min read


Homebuyers are watching the economy closely, and for good reason. Buying a home is one of the biggest purchases most people ever make. And some recession talk in the media has made a lot of would-be buyers second guess their plans.

In the latest LendingTree survey, almost 2 in 3 Americans said they think a recession is coming. And 74% of respondents say that’s having an impact on their financial decisions.

But here’s the good news: the experts aren’t nearly as concerned.

Most Americans Expect a Recession, But Most Experts Don’t

According to an October report from the Wall Street Journal (WSJ), only 1 in 3 experts surveyed say we may be headed for a recession sometime in the next 12 months (see graph below):

If the expert economists aren’t super worried, should you be? We’re not in a recession right now. And there’s no guarantee we’re heading into one.

What we do have is uncertainty – and the best way to handle that is by leaning on facts, not fear. You can do that by making sure you have the information you need to make an informed decision.

Tips for Buying a Home During Periods of Economic Uncertainty

Here’s the best advice anyone can give right now. While it’s important to keep an eye on what’s happening in the economy, that shouldn’t necessarily overshadow your real-life needs. Economic shifts come and go, but the reasons people buy homes rarely change. Danielle Hale, Chief Economist at Realtor.com, explains:

“Well-prepared buyers who have been waiting on the sidelines are likely motivated by personal and lifestyle needs like growing families, new jobs, or retirement. And these considerations can outweigh short-term economic uncertainties . . . ”

Timing your move around real life (not the news cycle) is what matters most.

But here’s the key. If you’re going to buy a home right now, job stability really matters. You need to feel confident in your income and know you can comfortably manage your mortgage payments, even if your situation or the economy shift.

If your job is secure and you’ve built a cushion of savings, experts say you don’t necessarily need to delay. Just keep these tips from the economists at Redfin in mind:

  • Set a budget and stick to it: Don’t overextend. Make sure your payments are affordable and your savings can cover any surprises. This includes factoring in costs likely to rise, like home insurance and taxes.
  • Negotiate: There are more homes for sale right now, and other buyers may pull back because of their own fears. That gives you more negotiating power when working with sellers. Use it to get the best deal possible.
  • Be strategic about payments and mortgage rates: Talk to lenders about what payment you can afford and the rate you can qualify for today, as well as your options if rates go down later on.
  • Consider selling before you buy: If you already own a home, selling first can reduce the financial pressure and help solidify your budget for your next home.

But nothing replaces the value of having a trusted team around you, especially right now. As Bankrate says:

“Buying a home during a recession can sometimes be a good idea – but only for people who are lucky enough to remain financially stable . . . Be sure to enlist the help of an experienced local real estate agent. Not only do agents know their markets well, they will also work to get you the best deal in any given situation, including a recession.”

Bottom Line

Most Americans think a recession is coming. But most experts don’t.

So, you don’t necessarily have to put your moving plans on hold. If your finances are solid, your job is stable, and you have a real need to move, you can still make it happen. 

What’s holding you back from making your next move? Let’s talk it over.

Filed Under: Reverse Mortgages

admin November 19, 2025

The Top 2 Things Homeowners Need To Know Before Selling

The Top 2 Things Homeowners Need To Know Before Selling

BLOGNovember 19, 2025

For SellersSelling TipsExpired/Withdrawn/CanceledPrice It Right/Overpricing


3 min read


Here’s something you should know before you sell your house. The homeowners who win in today’s market aren’t the ones waiting it out or stepping back. They’re the ones who adapt from the start.

A number of homeowners this year didn’t get the outcome they wanted. But it’s not because something’s wrong with the market. It’s because something wasn’t right with their expectations.

Realtor.com reports 57% more homes have been taken off the market compared to last year. That means they listed… but didn’t sell. But here’s the honest truth. It was mostly because of two things: price and timing.

And if the seller had come in with the right mindset on each, their sale would’ve gone differently. Here are the top 2 things you can learn from those other sellers.

1. Price It Right from Day 1

Let’s start with the most common sticking point: the asking price. Today, 8 in 10 sellers expect to get their asking price or more. But that confidence doesn’t always line up with reality.

According to Redfin, only 1 in 4 (25.3%) sellers are actually getting more than their list price.

And here’s where the mismatch is coming from.

A few years ago, you could set any price and buyers would come running, no matter what the price tag said. Odds are, you’d still sell for over asking. But things are different now.

Buyers have more options than they’ve had in years, so they can afford to be more selective. If your price feels even a little high to them, it’ll get overlooked in a heartbeat.

And for the homeowners who had that happen, some end up pulling their listings instead of making a simple adjustment that could have changed everything. Which is a shame, honestly. Because a small price tweak is usually all it takes to bring buyers in and get the deal done.

According to HousingWire, the average price cut right now is just 4%.

Think about that. Other sellers are listing too high and giving up rather than dropping their price 4%. If they’d just started 4% lower, they may have already sold. So, before you list, talk to your agent about what’s working nearby. They’ll help you find the sweet spot that’s competitive, realistic, and still protecting your bottom line.

And here’s the kicker. If you’ve been in your home for a while, your equity gives you room to set your list price more competitively and still come out way ahead. Unfortunately, those other sellers didn’t seem to realize that.

2. Don’t Rush the Process

Another common misstep: expecting your house to sell in a weekend.

Many sellers right now remember when homes sold in as little as hours – and they expect that to happen today. But in most markets, that’s not the reality anymore.

It takes closer to 60 days to go from listed to sold, which is actually normal (see the gray in the graph below):

It just feels slower because they’re comparing it to the lightning-fast pace of 2020 and 2021.

Think of it like driving 65 mph on the highway, then exiting and going 25. It feels like you’re crawling, but it’s actually the right speed for where you are. That’s what other sellers can’t seem to get over. But you can get ahead of that, by knowing what to expect.

Today’s buyers are more intentional. They’re taking their time, weighing their options, and making thoughtful decisions, which is creating a much healthier housing market.

So, if you’re planning to sell, don’t expect it to happen instantly. And don’t assume your house won’t sell if it doesn’t go under contract in the first weekend.

It’s normal for these things to take time.

If you want to make sure your house sells as quickly as possible, talk to your agent about ways to stand out, whether that’s through staging, photography, or strategic pricing. With the right advice, the right price, and the right prep work, it can still sell quickly.

Bottom Line

If you’re thinking about selling, don’t let the market discourage you, let it guide you. The listings that didn’t sell this year weren’t doomed. They just started with the wrong strategy.

You can still win if you price right, are patient, and work with a local agent who knows how to position your home from the start.

Because in today’s market, success isn’t about waiting for conditions to change. It’s about getting your expectations right from day one.

Filed Under: Reverse Mortgages

admin November 18, 2025

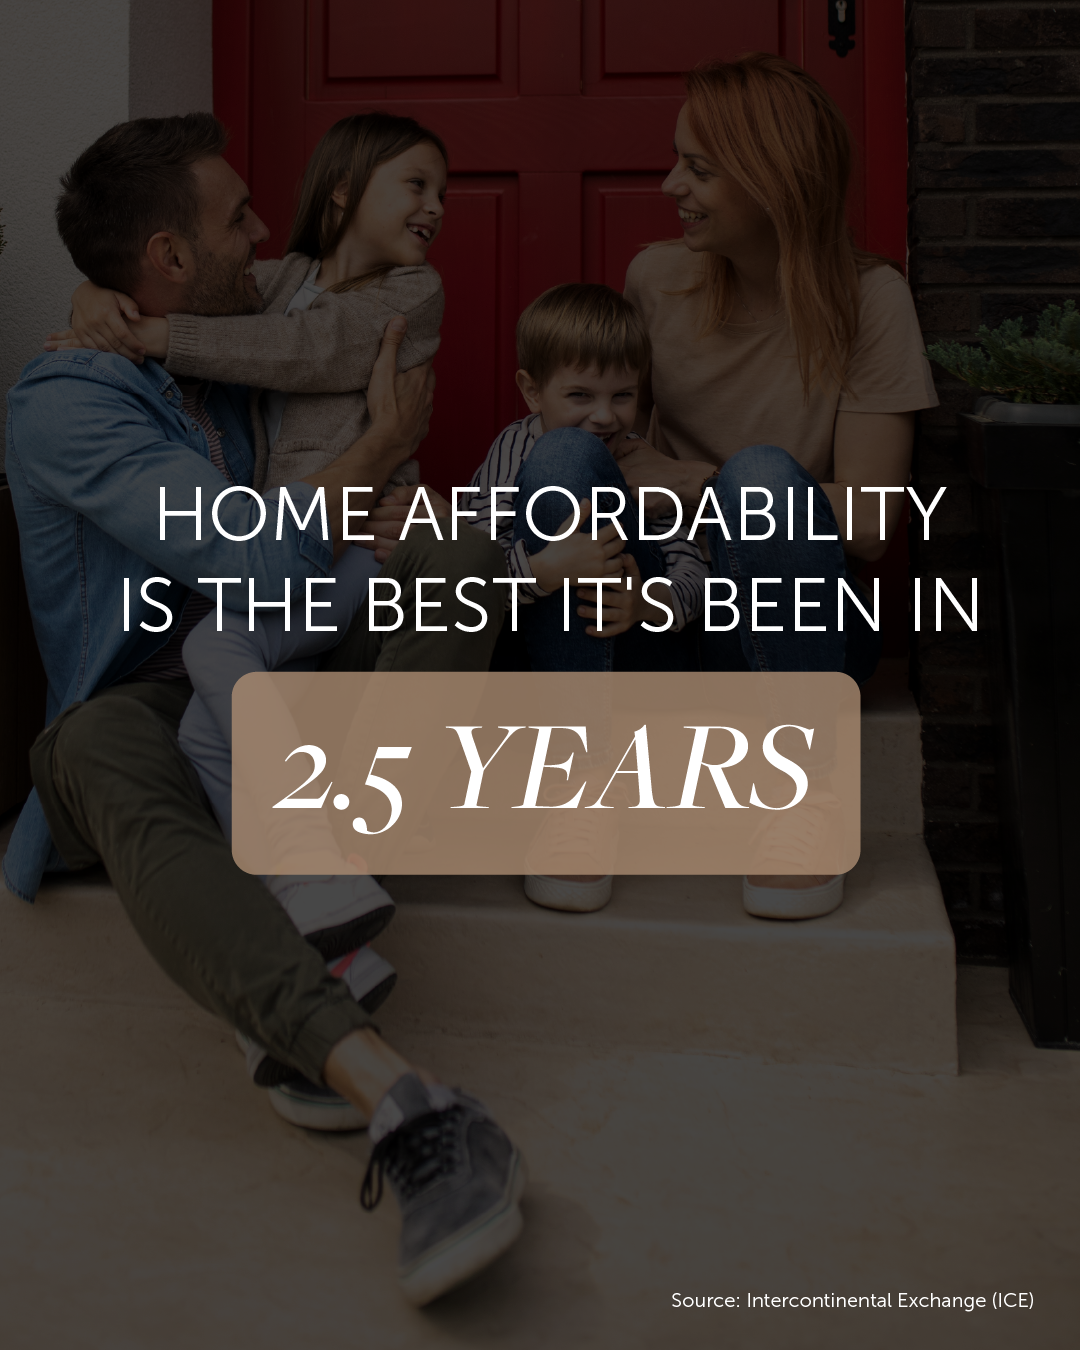
Home Affordability Is The Best It’s Been In 2.5 Years

Filed Under: Reverse Mortgages

admin November 17, 2025

The Housing Market Is Turning a Corner Going into 2026

The Housing Market Is Turning a Corner Going into 2026

BLOGNovember 17, 2025

For BuyersFor SellersMortgage RatesInventoryForecasts


3 min read


After several years of high mortgage rates and hesitation from buyers, momentum is quietly building beneath the surface of the housing market. Sellers are reappearing. Buyers are re-engaging. And for the first time in what feels like forever, there’s movement happening again.

No, it’s not a surge. But it is a shift – and it’s one that could set the stage for a stronger year in 2026.

So, what’s driving the comeback? Here are three big trends that are slowly breathing life back into the housing market right now.

1. Mortgage Rates Have Been Coming Down

Mortgage rates are always going to have their ups and downs – that’s just how rates work. Especially with the general economic uncertainty right now, some volatility is to be expected. But, if you zoom out, it’s the larger trend that really matters most.

And overall, rates have been trending down for most of this year (see graph below):

And in just the last few months, we’ve seen the best rates of 2025. According to Sam Khater, Chief Economist at Freddie Mac:

“On a median-priced home, this could allow a homebuyer to save thousands annually compared to earlier this year, showing that affordability is slowly improving.”

Here’s why that matters for you. This shift changes what you can actually afford. It means lower borrowing costs and more buying power. Take this as an example.

Data from Redfin shows a buyer with a $3,000 monthly budget can now afford roughly $25,000 more home than they could one year ago. That’s a big deal. And it’s just one of the reasons why activity is picking up.

2. More Homeowners Are Ready To Sell

For a while, many homeowners stayed put because they didn’t want to give up their low mortgage rate. That “lock-in effect” kept inventory tight. And while plenty of homeowners are still staying where they are today, the number of rate-locked homeowners is starting to ease as rates come down. Life changes are becoming a bigger part of what’s driving more people to move, and that’s opening up more inventory.

Data from Realtor.com shows just how much the number of homes for sale has grown. And the really interesting part is that the market is approaching levels that haven’t been seen for the past six years (see the blue on the graph below):

That return to more normal inventory levels is a really good thing. It gives buyers more options than they’ve had in years. And it’s helping to bring the market closer to balance.

3. More Buyers Are Re-Entering the Market

And it’s not just sellers making moves. With more options and slightly better affordability, buyers are getting back in the game, too. The Mortgage Bankers Association (MBA) reports purchase applications are up compared to last year, a clear signal that demand is building again (see graph below):

And experts think this momentum will continue. Economists from Fannie Mae, the Mortgage Bankers Association (MBA), and the National Association of Realtors (NAR) all forecast moderate sales growth going into 2026.

Now, this recovery won’t happen overnight. It’s not a flood of activity. But it is the start of steady improvement going into 2026. And that’s something a lot of people have been waiting for.

Bottom Line

After several slower-than-normal years, the market is finally starting to turn a corner. Declining mortgage rates, more listings, and growing buyer activity all point to a market gaining real traction.

Let’s connect to talk about what’s happening in our local market and how you can make the most of it in 2026.

Filed Under: Reverse Mortgages

admin November 13, 2025

Would You Let $80 a Month Hold You Back from Buying a Home?

Would You Let $80 a Month Hold You Back from Buying a Home?

BLOGNovember 13, 2025

For BuyersFirst-Time BuyersMortgage RatesAffordabilityForecasts


3 min read


A lot of buyers are stuck in “wait and see” mode right now. They’re watching rates hover a little above 6% and thinking, I’ll buy once they hit the 5s. Because who doesn’t want a better rate?

But here’s the thing: that 5.99% number might not save you as much as you think.

Affordability is still a challenge. There’s no question about that. But the market has given savvy buyers a head start. Mortgage rates have already come down over the past few months. And the drop we’ve seen saves you more than you’d think.

How Much You’ve Already Saved, Without Realizing It

Let’s put some real numbers to it. Rates peaked for the year in May when they inched above 7%. But since then, they’ve been slowly declining. Now, they’re sitting in the low 6s. And while that may not sound like a big deal, that change translates to real dollars.

According to data coming out of Redfin, the typical monthly payment on a $400,000 home is already down almost $400 since May.

That means if you’re buying a home now, you’re saving hundreds of dollars every month compared to what you would have been able to get earlier this spring. That’s real money that makes a real difference for buyers who paused their plans because they thought homeownership was out of reach.

And while it may be tempting to wait even longer to see bigger savings, that’s a gamble that could cost you. Here’s why.

Where Experts Say Rates Are Headed

For starters, most experts say mortgage rates are likely to stay pretty much where we are today throughout 2026. So, there’s no guarantee we’ll see a rate much lower than what we have now. Only one expert forecaster is saying rates could fall into the upper 5s next year (see graph below): 

And even if rates do dip below 6%, the extra savings you’re holding out for won’t move the needle as much as you might expect.

The Real Math Behind a 5.99% Rate

Let’s break it down. If rates come down to 5.99% from where they’ve been lately that’s a difference of only about $80 a month on an average priced home – give or take a bit based on your price point and the rate your lender quotes you (see chart below):

Eighty dollars. That’s it. And for the typical family, that’s about one dinner out (or one dinner in, if you have it delivered). That’s not enough to change the game for most buyers. But the savings of nearly $400 we already have compared to when you paused your search in the spring? That might be. 

So, the question to ask yourself is this:

Is an extra $80 savings really worth the wait?

Because while you’re holding out for that small dip, the bigger opportunity might be slipping away.

When Rates Fall, Competition Follows

Right now, you have more homes to choose from, sellers who are ready to negotiate to get a deal done, and fewer buyers to compete with. But once rates fall below 6%, buyer mindsets will shift and all of that will change.

The National Association of Realtors (NAR) reports that if rates hit 6%, about 5.5 million more households will be able to afford the median-priced home. Even if only a small fraction of them decide to buy, that could mean hundreds of thousands of buyers getting back into the market.

That creates more competition for you, which would push home prices even higher – maybe high enough to cancel out the extra savings you waited for.

So, if you’re waiting for rates below 6%, just keep in mind… that extra $80 may not be worth it in the grand scheme of things.

Bottom Line

You don’t have to wait for 5.99%. You have the chance to move (and save) right now. So, ask yourself: Would you let $80 hold you back from buying a home?

If you find a home you love and the math makes sense, getting ahead may be the best strategy. Let’s run your numbers so you can see what you’re working with in our market.

Filed Under: Reverse Mortgages

« Previous Page
Next Page »

Get More Information About East Coast Capital

Fill out the form below to learn more about Reverse Mortgages offered by East Coast Capital.

  • I agree to be contacted by Robert D. Gersh, via call, email, and text for mortgage services. To opt out, you can reply "stop" at any time or reply "help" for assistance. You can also click the unsubscribe link in the emails. Message and data rates may apply. Message frequency may vary. https://askbobgersh.com/privacy-policy/

Explore Our Site:

  • Questions
  • Are You Eligible for a Reverse Mortgage?
  • What About Counseling?
  • Moving Soon?
  • Have Use for the Money?
  • Want to stay in your own home?
  • Is a Reverse Mortgage Right for You?
  • One Time Large Expense?
  • What kind of home do you own?

Serving The Villages, Florida

Follow Us!

  • Facebook
  • LinkedIn
  • Twitter
  • YouTube

Our Newsroom:

  • A Mortgage Rate Buydown Could Make Your Next Home More Affordable
  • 3 Things Sellers Need To Know About Pricing Today
  • 3 Housing Questions That Might Come Up at Your Next Family Dinner
  • Homeowner Net Worth Has Nearly Doubled Since 2010
  • A Fixer-Upper Could Be Your Path To Homeownership

© 2026 · Bob Gersh, Reverse Mortgage Coordinator, East Coast Capital, 670 State Road 1st Floor, North Dartmouth, MA 02747 | Privacy Policy